

Welcome to the new subscribers that have joined us in the last week. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: Coinbase submits feedback on the GENIUS Act, Mastercard to partner with Ripple an Gemini.
Institutional Corner: Bank of England says its not falling behind on stablecoin regulation, Canada to release stablecoin regulation and Australia hoping to seize the moment on tokenisation.
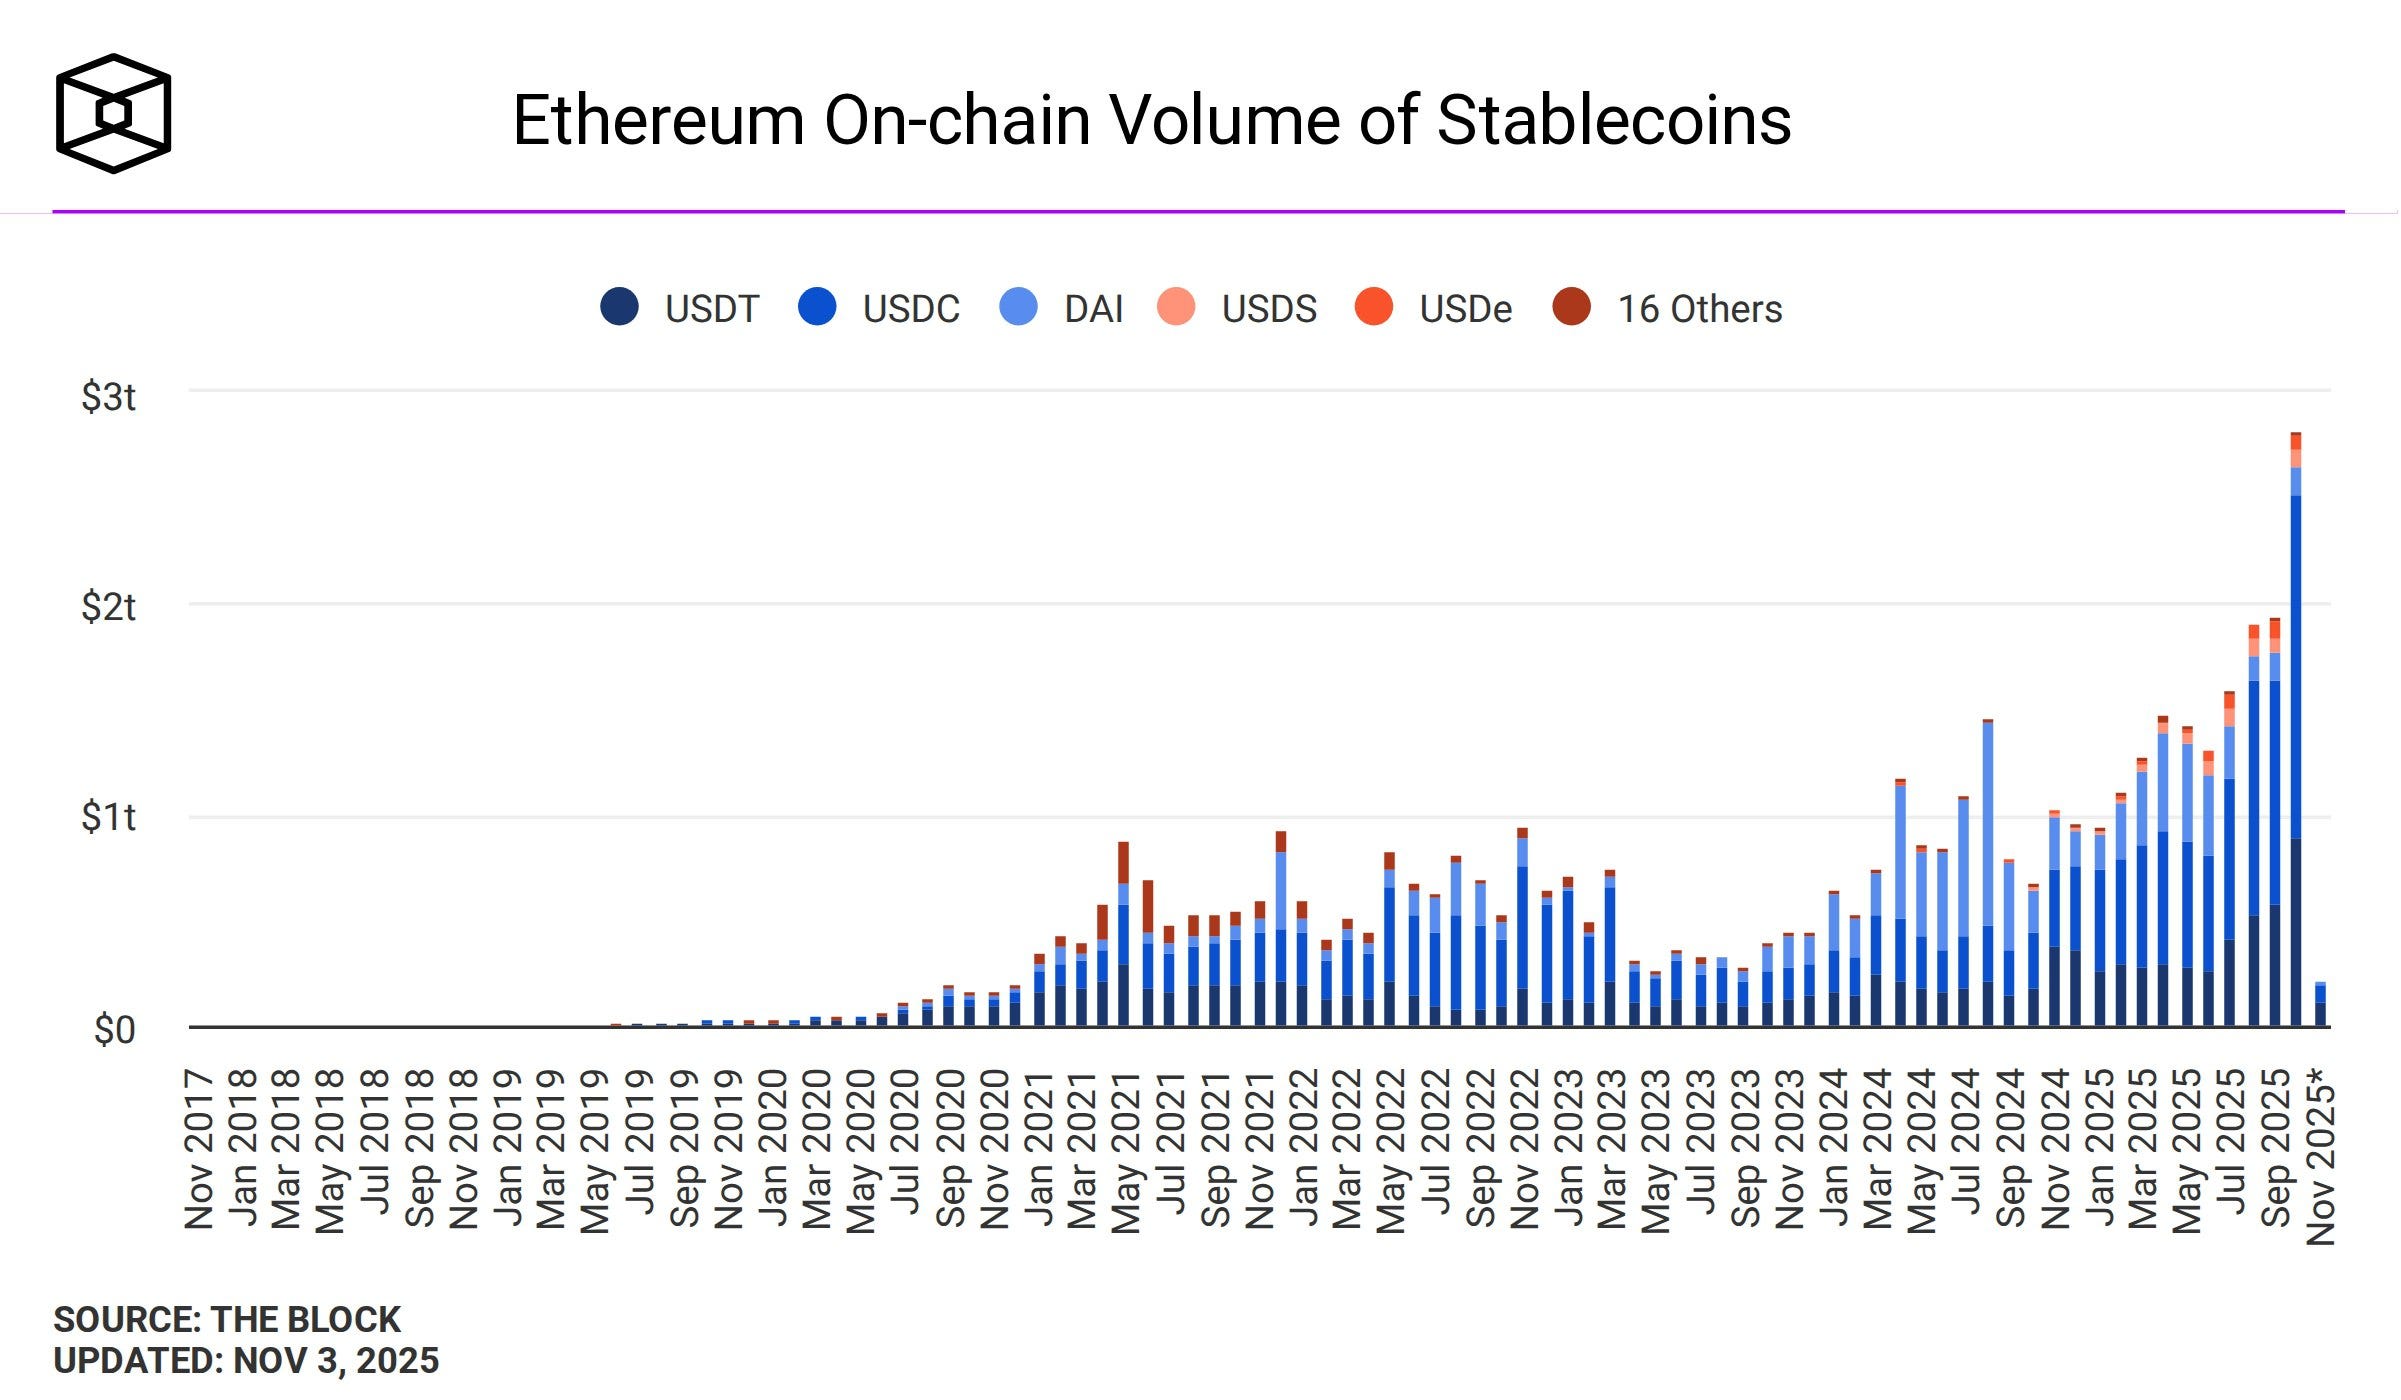
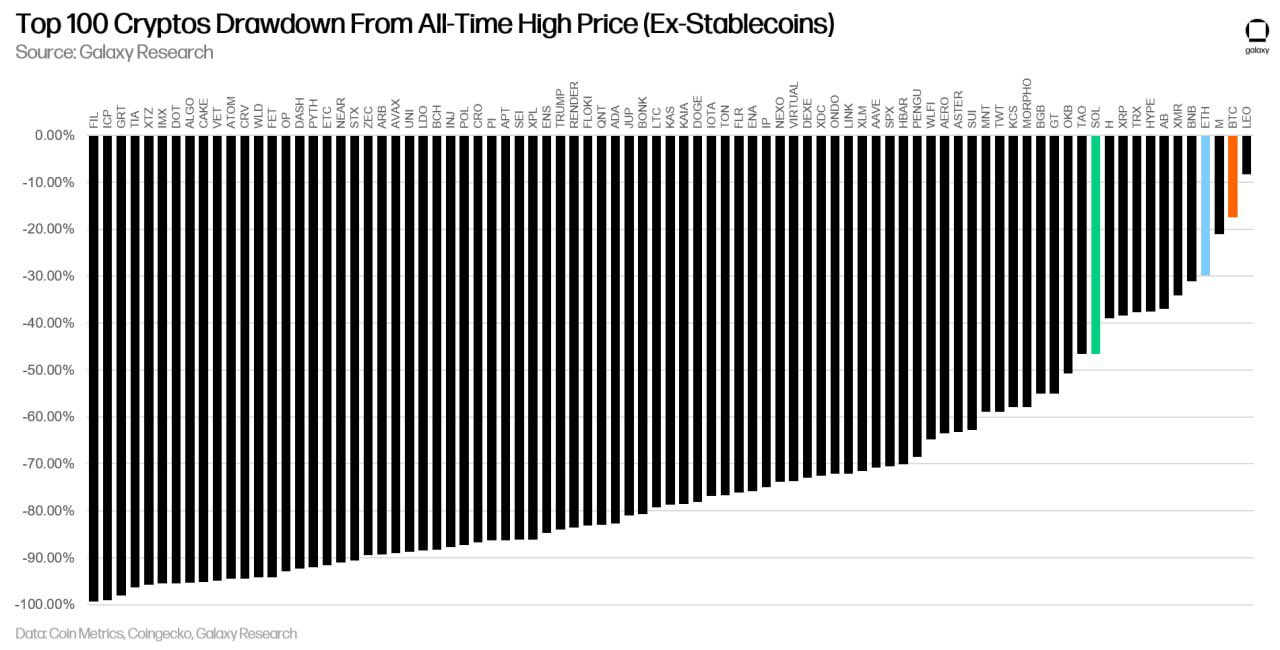
Charts of the Week: Monthly Ethereum stablecoin volume hits record $2.8 trillion in October, 72 of top 100 coins down by over 50%.
Top Jobs in Crypto: Featuring Robinhood, GK8, Bullish, BNY Mellon, Fasanara Capital, Susquehanna and Overchain.
Macro Update
This is where we connect the dots between macro and crypto.
A somewhat strange week for markets which traded with a lethargy, underpinned by caution. Tech stocks came under pressure and led broad equity indices lower, snapping a three week winning streak, driven on concerns of overvaluations and an AI bubble.
Of course, we remain in the camp that in AI related tech, we are witnessing a secular exponential trend for which markets, conditioned to think in terms of mean reversion, struggle to comprehend. And so periodically after weeks of relentless gains, a sense of fear and trepidation kicks in and we correct…before resuming the exponential uptrend. As we have said previously, as AI begins to replace not just jobs, but entire businesses and industries, we expect a large percentage of global equity value to transfer to AI tech stocks and we would remain comfortably long Nasdaq, notwithstanding the expected corrections along the way.
Bitcoin and the broader crypto space continues to trade heavily, with Bitcoin briefly dipping below $100k in the week, finding support ahead of $98k. Technically on the charts, if we were to break below there, a target of the $88k-92k zone is a reasonable target 🧐
This move lower came despite, as we suggested last week, the US liquidity backdrop easing. SOFR spreads tightened and usage of the Fed Standing Repo Facility (SRF) fell from a record $50bn on month end, to pretty much zero take up in the later part of the week - all signs of easier funding conditions. The Reverse Repo Facility (RRP) falling circa $45bn provided much needed cash to depleted bank reserves.
Nonetheless, with the government shut down reaching its longest on record, the TGA balance remains elevated (although off of its $1trn highs) and until this can be drawn down with the re-opening of government and subsequent spending to fund operations, the US liquidity impulse remains weak 😬
In need of a spark…
Add to this, we continue to see the Bitcoin “whales” selling, taking well deserved profits above $100k, whilst after the record liquidation event suffered a few weeks ago, there’s been a lot of capital destruction making the demand side weak, taking time to recover.
Yet looking this week across the macro-asset world, there’s nothing to materially concern us here. Following the “hawkish” FOMC inspired spike, US treasury yields broadly settled down, drifting lower after peaking Wednesday. Ditto the dollar. Oil trading around $60, inflation breakevens stable, Vix (equity market volatility) sub 20, MOVE Index (US bond market volatility) sub 75 - all a little bit “meh” 🥱
From the limited data currently available, we continue to see more signs of labour market weakness. This perhaps further weighed on broad risk given the delicate balance the Fed are juggling between downside labour market Vs upside inflation risks. ADP’s October employment report showed a modest rebound, with 42k private jobs added, but the underlying picture remains soft—hiring was narrow and sectors such as business services, information, and leisure/hospitality have now cut staff for three straight months. Challenger’s job cuts data reinforced that message, showing nearly 1.1 million layoffs year-to-date, up 65% versus last year, with October delivering the largest monthly cuts for this time of year since 2003.
In short: the labour market isn’t collapsing, but the cooling is broadening. This will likely keep the Fed engaged in rate cuts and we still favour a December cut, despite JPow downplaying it.
The ISM reports meanwhile continue to show the bifurcation between the services and manufacturing sectors of the economy. Services PMI bounced back into expansion at 52.4, with new orders at 56.2 hitting their strongest level in a year. Meanwhile, the Manufacturing PMI slipped again to 48.7, marking an eighth straight month of contraction as production and inventories cooled further.
Overall, little to change from our “Goldilocks” framing of the US macro. Slowing, not collapsing growth (indeed signs that economy is bottoming out) alongside sticky, not accelerating inflation. A sanguine backdrop and one that will allow the Fed to continue to ease rates ✅
As the week progressed, we shared the sense of market lethargy. Accepting that, with little macro catalysts and a tight US liquidity environment alongside the heavier supply dynamic, Bitcoin would continue to trade heavily. We need a spark to get us back above $107k to stave off the bearish momentum and that spark likely will come from the end of the government shutdown.
The beginning of “Not QE QE”...
However, in a week that was perhaps unremarkable, Friday we got a speech from the NY Fed’s John Williams (speaking at an ECB conference) which we think could be very significant for markets 🚨
We’ve written a lot in recent weeks about some of the mechanics and plumbing in the US banking system that are important determinants of market liquidity - from RRP, to TGA, SRF, to IOBR to name but a few acronyms!
Williams’ speech titled “Theory and Practice of Monetary Policy Implementation” gave a good overview of these tools and how they are used to manage and ensure “ample” levels of bank reserves in the system. In layman terms, how they ensure sufficient liquidity to allow normal market functioning. It’s worth taking a moment to read his speech:
https://www.newyorkfed.org/newsevents/speeches/2025/wil251107
We highlighted just 2 weeks ago a similar 29th Sep speech from Julie Remache, Head of Market and Portfolio Analysis at the NY Fed. In this she alluded to the need to stop the balance sheet run off (aka Quantitative Tightening - QT) with reserves transitioning from abundant to ample. We took this as a subtle hint that the Fed would end QT and indeed, they announced the end of QT at the Oct FOMC.
We believe in this speech, Williams has signalled to the market that the Fed is set to start purchasing assets again, expanding the balance sheet.
To wit:
“Looking forward, the next step in our balance sheet strategy will be to assess when the level of reserves has reached ample. It will then be the time to begin the process of gradual purchases of assets that will maintain an ample level of reserves…Based on recent sustained repo market pressures and other growing signs of reserves moving from abundant to ample, I expect that it will not be long before we reach ample reserves”.
This is a HUGE signal that what we term “Not QE QE” is set to be implemented to get ahead of the expected funding crunch into year end.
Effectively, this will mean the Fed, via some form of monetary operation, will start purchasing Treasury Bills and funding the deficit, under the guise of supplying market liquidity and ensuring ample levels of bank reserves.
It certainly won’t be called QE and will be passed off simply as a “technical” operation that is distinct from monetary policy. “Macro doomers” will write endlessly why this is NOT QE - for which we agree. It’s not QE in it’s intent and purpose and also in terms of its duration (fwiw, we dealt for many years with the same people saying QE will have no impact on asset prices as technically it’s simply an “asset swap” of treasuries for bank reserves that aren’t allowed to be lent out. Clearly overlooking how it would facilitate leverage and risk taking in the system)
Yet it has the same impact as QE via the liquidity it provides to the system and, by printing money, it’s accelerating the debasement of currency.
Nothing stops this train…
Once again, it brings us back to our long term bull thesis for Bitcoin. Fiat systems built on debt, require ever more debt to grow which will require ever more liquidity (read money printing) to maintain “normal market functioning” and avoid a redux of the 2008 Global Financial Crisis (GFC). Nominal growth simply can’t outpace the debt and so eventually, it needs to be financed by the central bank money printer. Nothing stops this train!
We had QE 1,2,3 and 4 post the GFC and the big injection of cash in 2020/2021. That built excess reserves that facilitated the funding of the US deficit and sent asset markets higher.
Now as those excess reserves run dry, the Fed is readying the printer for the next wave of balance sheet expansion and next leg of the currency debasement trade. For this reason, we find it difficult to believe the bull market is over.
In fact, as the Fed money printers start to switch on again, we’re likely just getting started.
Native News
Key news from the crypto native space this week.
Coinbase submitted feedback to the US Treasury on the GENIUS Act this week. Coinbase noted that Treasury should avoid imposing requirements beyond what the statute explicitly commands, warning that overreach could stifle innovation and undermine the law’s goal of making the U.S. the “crypto capital of the world.” Specifically, Coinbase called on regulators to apply a narrow reading of the law, excluding non-financial software, blockchain validators, and open-source protocols from its scope. It noted that the Act’s interest-payment prohibition applies only to stablecoin issuers — not to intermediaries or exchanges that offer loyalty rewards. “Treating third‐party rewards or loyalty programs as prohibited ‘interest’ would rewrite Congress’s carefully-drawn lines and conflict with the statuteʼs text and purpose,” said the company. Read the full response from Coinbase HERE.
Credit card company Mastercard said this week that it is teaming up with Gemini and Ripple to explore using RLUSD stablecoins, on XRPL, to settle fiat card transactions. XRPL Ledger, is an open-source blockchain primarily used to enhance payment capabilities. Gemini is a crypto trading platform founded by Cameron and Tyler Winklevoss in 2014. The company offers an XRP edition of its credit card with help of WebBank. Read the full statement from Ripple HERE.
Institutional Corner
Top stories from the big institutions
Speaking at conference, Bank of England Deputy Governor Sarah Breeden played down concerns the U.K. is slipping behind other jurisdictions in introducing regulatory regimes for stablecoins, saying the rules will be in effect “just as quickly as the U.S.” Breeden, the deputy governor for financial stability said “Our aim is to make sure that our regime is up and running, just as quickly as the U.S.” Its been well reported that the BOE planned to limit the amount of stablecoins that individuals and businesses could own. Breeden described these plans as “less of an issue in practice than people might think.” She pointed to differences in the U.K. mortgage market compared with the U.S., where the GENIUS Act was signed into law by President Trump in July, as a reason for a limit on stablecoin holdings being necessary. “People in the U.S. get their mortgages from Fannie and Freddie, and they’re funded in financial markets,” Breeden said, referring to the Federal National Mortgage Association (known as Fannie Mae) and Federal Home Loan Mortgage Corp. (Freddie Mac). “People in the U.K. get their mortgages from commercial banks and so that need for limits as we transition to a world of stablecoins is one that is less pertinent to the U.S. regime.”
Canada released its budget on Tuesday and said that it is set to release legislation regulating fiat backed stablecoins. According to the details, stablecoin issuers will be required to hold sufficient reserves, establish redemption policies and implement various risk management frameworks, including measures to protect personal and financial data. The Bank of Canada will apparently allocate $10 million over two years, starting in the 2026-2027 fiscal year, to ensure everything runs smoothly, followed by an estimated $5 million in annual costs that will be offset from stablecoin issuers regulated under the Retail Payment Activities Act. Read the full budget document HERE.
Speaking on Tokenisation, Australian Securities and Investments Commission (ASIC) Chair Joe Longo said that the country must “seize the opportunity or be left behind” as tokenisation transforms capital markets worldwide. Longo noted that tokenisation “could fundamentally transform our capital markets” by breaking assets into smaller, tradable units and enabling instant settlement. Yet Australia risks becoming the “land of missed opportunity,” Longo warned, as other nations forge ahead. He noted that Switzerland’s digital securities exchange has surpassed $3.1 billion in tokenised bond issuances since 2021. J.P. Morgan plans to fully tokenise its money market funds within two years, according to Longo. Nasdaq has proposed launching 24-hour tokenised securities trading by late next year. “Once, Australia was one of the early adopters of innovation in markets,” Longo said, noting the country’s pioneering electronic trading systems. “Now, other countries are outpacing us.” Read the full speech from Longo HERE.
Charts of the Week
Because charts are just as important as macro.
Monthly Ethereum stablecoin volume hits record $2.8 trillion in October.
72 of the top 100 cryptos by market cap are -50% or more from their prior all-time highs.
Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Business Development Lead - Crypto, at Robinhood
Director of Sales - Europe at GK8
Manager, Exchange Sales at Bullish
Product Development Manager - Blockchain/Digital Assets/Payments at BNY Mellon
Backend DeFi Developer at Fasanara Capital
Crypto Research Analyst at Susquehanna
Head of Institutional Lending at Overchain
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.
Loved this one — that “lethargy underpinned by caution” line hit.
We’ve been seeing the same thing: liquidity hasn’t dried up, it just stopped absorbing risk and started transmitting it downstream.
Wrote about that dynamic in our latest piece — would love to hear your take lighthousemacro.com/p/liquidity-transmission-framework
Great post!! Hopefully this week the shutdown ends …