

Welcome to the new subscribers that have joined us in the last week. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: Binance releases its latest Proof of Reserves, Western Union to release a stablecoin card.
Institutional Corner: Digital assets legally recognised as a form of property in the UK, SEC Chair says he expects the US financial market to integrate blockchain technology within 2 years, Larry Fink answers questions on crypto and bitcoin.
Charts of the Week: Average cost to produce 1 BTC has risen, retail investors hold a significant amount of spot BTC ETF’s.
Top Jobs in Crypto: Featuring Fireblocks, Kraken, GSR, BNY Mellon, Binance, BCB Group, Coinbase
Macro Update
This is where we connect the dots between macro and crypto.
Firing Up the Fed Money Printer
Equity markets began December on the front foot, extending last week’s gains as markets lean harder into a December Fed cut. Trading volumes were light, but the Nasdaq again led as managers continued to reluctantly re-weight higher.
The interesting divergence remains crypto: while equities are leaning into the easing narrative and a benign macro backdrop, Bitcoin continues to trade a choppy range, sensitive to the on-going stress in US funding markets.
Wednesday’s FOMC will therefore not be about the widely expected 25bps cut—it will be about whether the Fed moves early to ease reserve scarcity. Our base case remains that they announce what we have termed “not-QE QE”: monthly T-bill purchases that directly inject reserves into the banking system and suppress front-end rates. That would be a dovish surprise and would likely see Bitcoin reverse sharply higher. Without it, funding tightness remains into year-end and patience will be required.
Not too hot, not too cold…
On the data front, our “goldilocks” framing is still very much intact. Despite manufacturing remaining in contraction territory, with the ISM slipping to 48.2, services surprised to the upside, expanding at the fastest pace since February at 52.6. Crucially, service-sector input prices cooled sharply. The Fed’s favoured inflation measure, Core PCE printed 0.2% MoM and 2.8% YoY, broadly unchanged. Sticky, not accelerating inflation, with an economy slowing, not collapsing.
The labour market still looks soft. Private payrolls fell by 32k—the weakest print since early 2023—while corporate layoff announcements hit their highest year-to-date total since COVID. Yet claims data moved the other way, falling to the lowest since 2022. Softening sufficiently to warrant rate cuts, without causing recessionary angst.
Yen sacrifice…
The biggest cause for concern currently comes from the Japanese bond market. After BoJ governor Ueda issued a hawkish speech, laying the groundwork for a December hike, Japanese bonds sold off sharply, sending 10yr yields to near 2%, a level not seen since 2007. This seemed to weigh on US Treasuries, dragging 10yr yields higher to 4.14% and re-igniting the “carry unwind” FUD.
Again, we continue to dismiss these fears as the big Japanese investors (Life insurance companies and pension funds) that are largely responsible for the circa $4trn in net foreign held assets, rarely adjust their portfolios and are unlikely to do so now to repatriate home in search of these higher yields, especially as the hikes are coming for the “wrong reasons” - fighting a toxic stagflationary combo. In fact, domestic institutions sold ~10.7trn Yen of Japanese Government Bonds (JGB’s) in September.
The Bank of Japan faces an impossible situation and will be forced to either save the bond market or the currency and sacrificing the currency will be seen as the lesser of two evils. Consequently, as the bond market comes under pressure, the BoJ will be forced to increase JGB purchases to “smooth” the volatility, injecting more liquidity into the market. These conflicting actions of hiking rates and forced JGB purchases will likely keep the JPY under pressure, encouraging outflows from Japan, with US assets likely a beneficiary.
So whilst there’s reason for short term caution given the potential for contagion from Japanese bond markets to global bond markets, we don’t see reasons for a huge “carry unwind” and mass selling of foreign assets by Japanese investors to repatriate home. Indeed, the MOVE index (measure of US Treasury volatility) moved lower last week to sit at its lowest levels since late 2021, suggesting little sign of contagion fears.
Breaking the four year cycle…
All in all, as we head into the Fed, the cross-asset macro generally looks supportive for risk. Despite Japan, US bond volatility is subdued, ditto for equity market volatility with the Vix sub 16. The dollar is also slowly softening again, oil remains subdued and financial conditions are loosening.
Bitcoin is being strangled by the tightness in US funding markets and we look to the Fed announcing liquidity operations on Wednesday to loosen the noose. Without that, patience will be required as investors look ahead to 2026.
One thing is for sure, for those who still believe in the 4 year Bitcoin cycle, the macro set up heading into 2026 is vastly different to that of when we moved into 2022. Then, the Fed was about to shift into a rapid tightening and liquidity draining cycle. Now, we’re moving into a continued rate cutting cycle accompanied by balance sheet expansion as the Fed effectively turns on the money printers to monetise the deficit. That’s a powerful, structural tide to be swimming against in the new year.
Native News
Key news from the crypto native space this week.
Binance released its 37th Proof of Reserves as of 1 December. User BTC holdings reached 617,620 BTC, up 4% from 1 November. (+23,768 BTC). User ETH holdings fell 1.32% to 4.04 million ETH (-54,257 ETH). User USDT holdings slipped 1.24% to 34.3 billion USDT (-430 million USDT). Read the full release from Binance HERE.
Western Union is developing a prepaid stablecoin card for countries with high inflation. CFO Matthew Cagwin stated at the UBS Global Technology and AI Conference that the product aims to help users protect purchasing power from rapid currency depreciation. For example, in Argentina, where inflation exceeded 200% last year, a USD-pegged stablecoin card helps preserve value. Western Union also plans to launch the USD stablecoin USDPT on Solana in early 2026.
Institutional Corner
Top stories from the big institutions
The UK’s crypto regulation reached a major milestone on Tuesday after the Property (Digital Assets etc.) Act 2025 received Royal Assent from King Charles III, legally recognising digital assets as a form of property. The short bill, which passed both houses of Parliament without amendment, confirms that digital holdings such as bitcoin and stablecoins can be the subject of property rights distinct from traditional categories of physical objects or contractual rights. CryptoUK, the country’s first crypto and blockchain industry trade association, said on X that UK courts have already been treating crypto as property through case-by-case judgments. Having that actually written into law will provide clearer legal pathways for crypto-related crimes or litigations, the association said.
SEC chair Paul Atkins said he expects the entire U.S. financial market to migrate to blockchain infrastructure within the next two years. He saisd that the next step is coming with digital assets, digitalisation and tokenisation of the market, bringing “significant benefits” in transparency and risk management. Watch the full interview HERE.
Speaking at The New York Times’ DealBook Summit on Wednesday, BlackRock CEO Larry Fink addressed questions related to his views on crypto and Bitcoin. The BlackRock CEO said his move from associating crypto primarily with money laundering to having exposure to billions of dollars in BTC was “a very glaring public example of a big shift in [his] opinions.” Fink, who took the stage with Coinbase CEO Brian Armstrong, was not entirely bullish on Bitcoin describing Bitcoin as “an asset of fear,” noting that the price of the cryptocurrency had dropped amid news of a US-China trade deal and a potential end to the war in Ukraine. He added “If you bought [Bitcoin] for a trade, it’s a very volatile asset. You’re going to have to be really good at market timing, which most people aren’t.”
Charts of the Week
Because charts are just as important as macro.
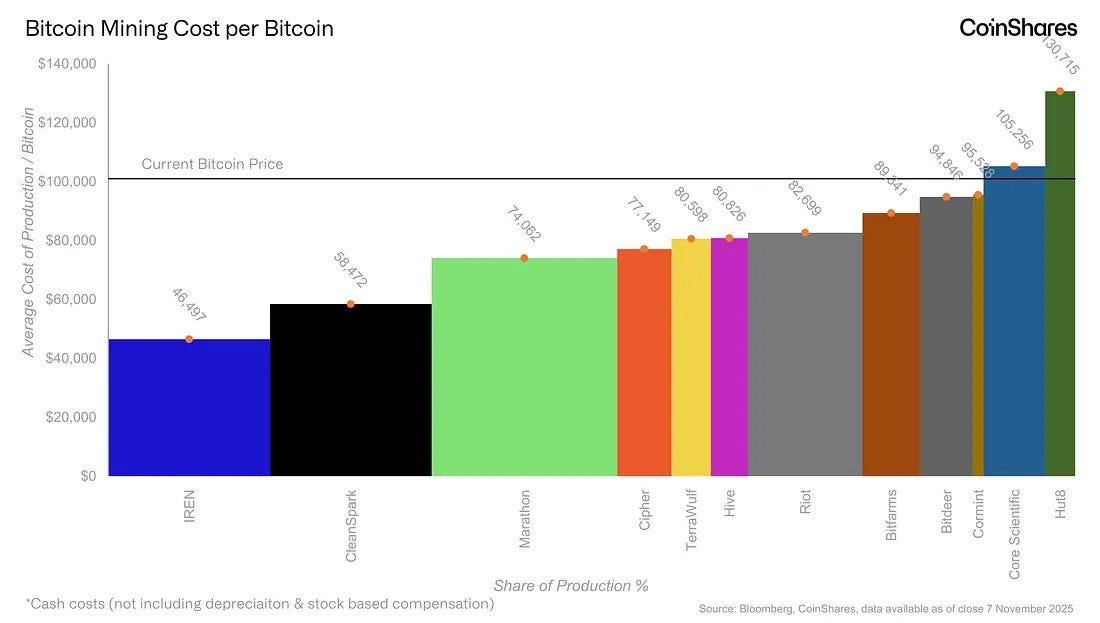
The average cash cost to produce one Bitcoin among publicly listed miners rose to approximately $74,600 in Q2 2025. When factoring in non-cash costs such as depreciation and stock-based compensation, the total average cost climbed to $137,800
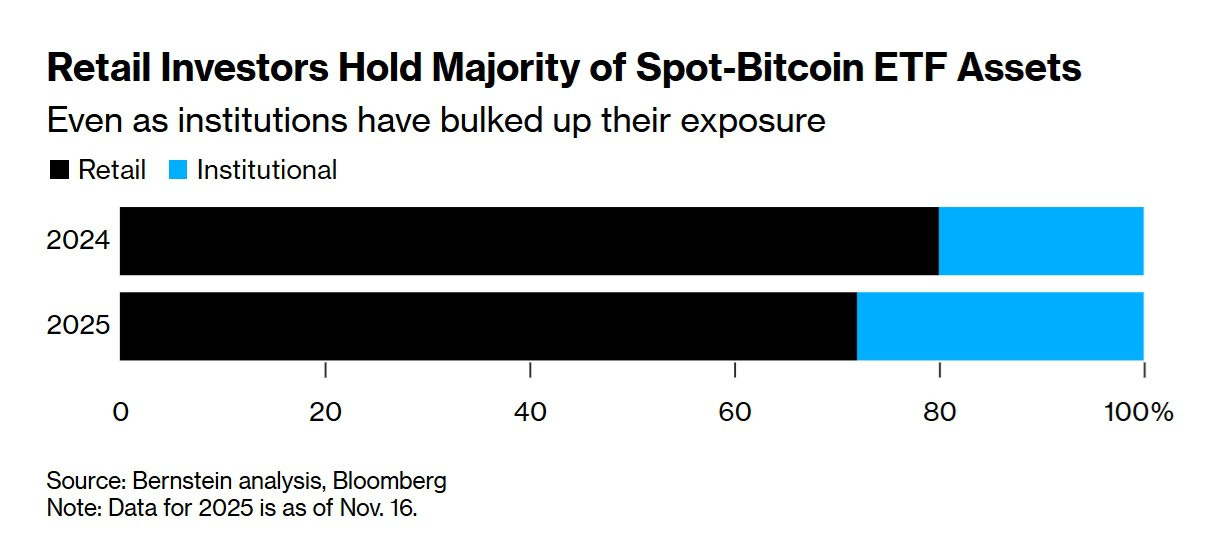
According to Bernstein’s analysis, retail investors hold a significant majority of spot-Bitcoin ETF assets, accounting for approximately three-quarters of the total.
Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Sales Director Payments at Fireblocks
Middle Office Manager EU at Kraken
Director, Product and Innovation - Tokenisation at BNY Mellon
Listing Business Development at Binance
Senior Product Analyst for Crypto at BCB Group
Technical Account Manager at Coinbase
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.