

Were back with our first newsletter of 2026. Thanks again for all of the support and good luck for the year ahead.
Welcome to the new subscribers that have joined us in the last week. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: World Liberty Finance files an application to form a national trust bank, Stand With Crypto sees large sign ups in 2025.
Institutional Corner: UK FCA announces a new crypto regime to start in Oct 2027, Morgan Stanley to launch bitcoin, ether, and solana trading on its E-Trade platform alongside plans for a proprietary digital wallet, BNY Mellon to launch a new tokenised deposit service, JP Morgan to launch JPM Coin on Canton Network.
Charts of the Week: 2025 the least volatile year in BTC history, Phantom generates more revenue than other DeFi wallets put together, the cryptocurrency industry witnessed over $3.4Bn in theft last year.
Top Jobs in Crypto: Featuring Goldman Sachs, Kraken, BNY Mellon, Visa, Gemini, Keyrock and Crypto.com
Macro Update
This is where we connect the dots between macro and crypto.
Running it Hot
Equity markets have started the year on the front foot, with most major indices clocking new record highs in the first full trading week of the year. Notably, small caps led the move, with the Russell 2000 clocking a 4.6% gain on the week, underscoring easier financial conditions and stronger US growth ahead 💪
Geopolitical uncertainty lingered in the background post the US capture of the Venezuelan President, Maduro and his wife. Oil initially trading lower given the vast level of oil reserves in Venezuela, amongst the largest in the world. Although reality quickly set in that significant capital and infrastructure rebuilding will be required before meaningful changes to output can occur.
Data wise, we continue to see a familiar pattern play out as we enter 2026. The ISM data showing activity in the manufacturing sector remains in contraction, declining 0.3 points to 47.9, whilst the more important services expanded for the 10th month in a row at 54.4 up from 52.6. New orders leading the expansion and encouragingly, price pressures softened a touch.
K-shaped economy
The “macro doomer’s” incessant calls for recession once again look likely to be frustrated. Indeed, the Atlanta Fed’s GDPNow forecast for Q4 2025 jumped from ~2.7% to 5.4% annualized, reflecting stronger trade data. Whilst these forecasts are very volatile (and skewed by gold exports), US growth heading into Q1 remains robust, which we continue to expect when fiscal deficits are running north of 6%.
The labour market however continues to reveal a soft underbelly, with Non Farm Payrolls showing the US added a below consensus 50k jobs in December, with October and November readings revised a combined 76k lower. Given JPow recently said the Fed believes NFP numbers are overstated by ~60k, this is a negative print from the Fed’s purview. Meanwhile, the JOLTS report for November showed a slowdown in hiring from 5.4mio to 5.1mio with job openings at the lowest level since Sep 2024 at 7.1mio.
The K-shape economy persists: asset prices and services activity remain resilient, with cash rich sectors like tech achieving prosperity, while employment momentum continues to erode beneath the surface.
For a Fed balancing the risks between inflation and employment, the bigger threat appears to be coming from the labour market. With the market only priced for 2 cuts in 2026, we think there is plenty of scope for that pricing to move dovishly and indeed for the Fed to deliver more than expected. Either way, from a big picture point of view, we continue to move towards a lower rate environment, which will provide a persistent tailwind for risk in 2026.
QE-lite getting fatter…
Other big news this week came from Trump’s announcement that he’s instructing the mortgage agencies, Fannie Mae and Freddie Mac, to purchase $200bn in Mortgage Backed Securities (MBS) to drive down mortgage rates and improve housing affordability 👀
We wrote in our final piece of 2025 how the Fed’s announcement of $40bn monthly T-bill purchases (or Reserve Management Purchases - RMP) were a form of “QE-lite”. Alongside the “treasury QE” whereby treasury issuance has been weighted toward T-bills (which the Fed are printing the money to buy) plus the Supplementary Leverage Ratio (SLR) adjustments encouraging banks to purchase more longer date, US treasuries, this feels like another piece of “monetary alchemy” to lower rates and enact pseudo Quantitative Easing.
Especially, keep in mind that the Fed’s maturing holdings of MBS are now being re-invested into Treasuries (circa $20bn a month)
So we have the Treasury weighting debt issuance towards T-bills and relatively reducing the amount of longer dated treasuries, or “duration” in the market. The Fed is printing $40bn a month to purchase T-bills. Banks will be encouraged to buy more treasuries with the SLR amendments and now the mortgage agencies will purchase $200bn in MBS. We’re moving closer to “full-fat” QE with the Treasury effectively now in control of monetary policy. This is before Trump’s pick for Fed chair takes his place. This is fiscal dominance in action, with monetary policy increasingly subordinated to political and electoral objectives.
No doubt as we head into the mid-terms in November, Trump and Bessent will continue to hand out the candy and they look determined to “run it hot.”
We continue therefore to see 2026 as a very strong year for risk assets broadly. Global liquidity continues to rise and now, with the Fed balance sheet back in expansion mode, US liquidity will turn from a headwind to a tailwind.
Easing supply pressure
This should finally start to feed through to Bitcoin. We were frustrated in our calls for Bitcoin to 150k in 2025 as the positive macro tailwinds faced persistent selling above $100k by the crypto “whales” whilst the tightening in US liquidity conditions in Q4, alongside the destructive impact of the 10th October liquidation event, negatively impacted demand.
On-chain analytics now suggest reduced profit taking and consequent supply pressure from whales and long term holders, with realised price gains decelerating. As shown in the chart below from our friends at Glassnode, realised profit (7D-SMA) has declined from above the $1bn per day observed in much of Q4 to below 185mio per day 👇
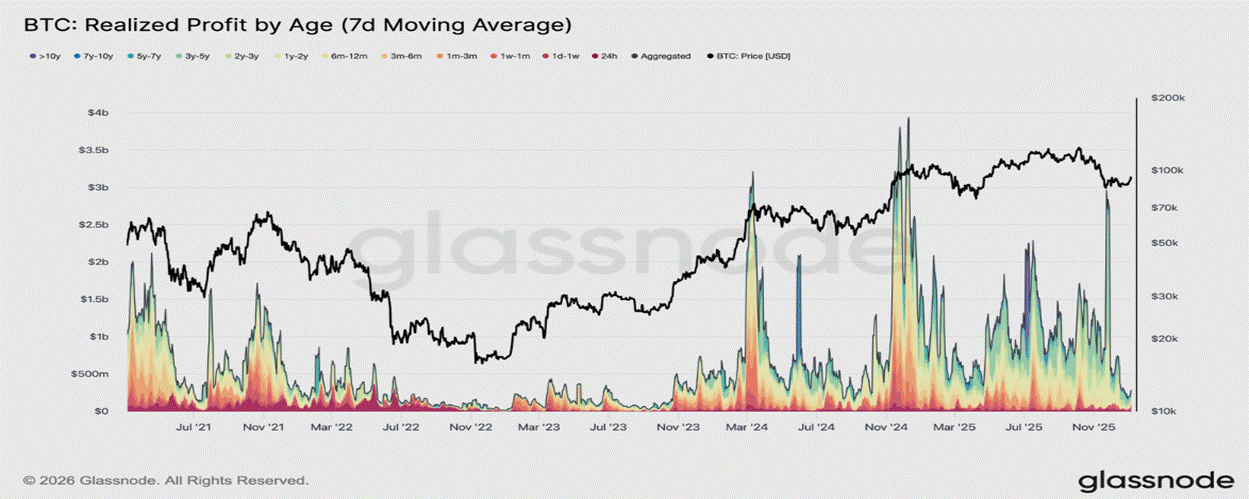
Profit taking pressure has subsequently eased significantly, although as Glassnode notes, “this relief rally is now pushing into a structurally different supply regime”. That is, recent “top buyers” with a cost basis distributed between $92k-$117k now become a persistent sell-side headwind as they likely look to exit at breakeven, having ridden the market down towards 80k.
Indeed, after a positive start, net ETF flows were negative again this past week. So despite the positive tailwinds from the macro and liquidity side, which an “underweight” equity market has duly benefitted from, Bitcoin’s attempts to move higher continue to be frustrated.
We are however in the bottoming out process and as these negative supply factors continue to be absorbed, what we’re seeing with rising global liquidity, easing financial conditions, an expansive Fed balance sheet, “Treasury QE” and the Trump administration looking to “run it hot” into the mid-terms, the “debasement trade” is set to go into overdrive.
Bitcoin, we continue to believe will be the best expression of this trade and will regain its throne as the number 1 performing macro asset in 2026 🚀
Native News
Key news from the crypto native space this week.
World Liberty Financial, a crypto venture linked to President Donald Trump’s family, has filed an application with the U.S. Office of the Comptroller of the Currency to form a national trust bank. The proposal seeks to place its USD1 stablecoin under direct federal supervision in a regulatory category that has admitted only one other crypto-native firm to date. If approved, the proposed entity named as World Liberty Trust Company, will be allowed to “take over the issuance and redemption of USD1, offer conversion services from other major stablecoins into USD1, offer custody services for fiat and major stablecoins, and perform the reserve management for the assets backing outstanding USD1.
The digital assets advocacy group Stand With Crypto grew by 675,000 online signups last year, reaching about 2.6 million in the U.S. The group has been deploying its members into political letter-writing campaigns to support U.S. crypto legislation, totaling 925,000 in 2025 and more than a million emails since its founding. Coinbase set up Stand With Crypto in 2023 and funded its initial activity, and it remains a partner and donor alongside other companies, such as Kraken, Gemini, Anchorage Digital and Paradigm, in addition to donations from members.
Institutional Corner
Top stories from the big institutions
UK's FCA will open the crypto licensing gateway in September 2026, ahead of a new regime taking effect in October 2027. Existing AML or payments registrations will not carry over and must be re-approved. Firms that miss approval deadlines will be placed in a transitional regime, limited to existing services with restrictions on new offerings. Read the full details from the FCA HERE.
Jedd Finn, Morgan Stanley’s head of wealth management said this week that the investment bank plans to launch bitcoin, ether, and solana trading on its E-Trade platform in the first half of this year, alongside plans for a proprietary digital wallet. Finn said in an interview that “This is really a recognition that the way that financial service infrastructure works is going to change. Over time, as our infrastructure develops, we’ll be able to do more with the blending of the traditional finance, or tradfi, and decentralised finance, or defi, ecosystems.” The report comes the same week Morgan Stanley filed S-1 registration statements with the U.S. Securities and Exchange Commission for its own bitcoin, ether, and solana exchange-traded funds — a move that caught even veteran ETF analysts off guard. Bloomberg Intelligence analyst James Seyffart wrote in an X post on Tuesday that he “Didn’t see this coming.”
Bank of New York Mellon Corp. has launched a new tokenised deposit service designed to let institutional clients move funds using blockchain rails. The bank said on Friday that the product creates a form of digital cash that exists as an on-chain representation of deposits already held in client accounts at BNY. Moreover, this approach keeps underlying balances within the traditional banking environment while enabling on-chain transfers. According to BNY, the new structure turns client balances into on-chain deposits that can circulate over blockchain payment rails while remaining fully backed by funds at the bank. However, the tokenized representation is intended as a technical wrapper, not a separate asset, and mirrors the underlying account position. The institution highlighted several intended use cases, including collateral and margin movements within trading and clearing workflows. That said, the model also targets faster corporate and institutional payments where intraday liquidity and precise settlement timing are critical.
JPMorgan’s Kinexys blockchain unit announced plans Wednesday to launch its JPM Coin on Canton Network, the rising privacy-enabled network designed for financial markets. The firm is working with Digital Asset, the company behind Canton, to expand the token’s reach. Initially launched on Base, the Coinbase-incubated Ethereum layer-2 scaling network, JPM Coin is a bank-issued, USD-denominated deposit token that lets institutional clients make payments using a digital representation of JPMorgan deposits on public blockchain infrastructure. The collaboration will proceed in phases throughout 2026, initially focusing on establishing technical and business frameworks for JPM Coin's issuance, transfer, and redemption on Canton. Once natively available on Canton, institutions will be able to issue, transfer, and redeem JPMD near-instantly.
Charts of the Week
Because charts are just as important as macro.
2025 was the least volatile year in BTC history to date.

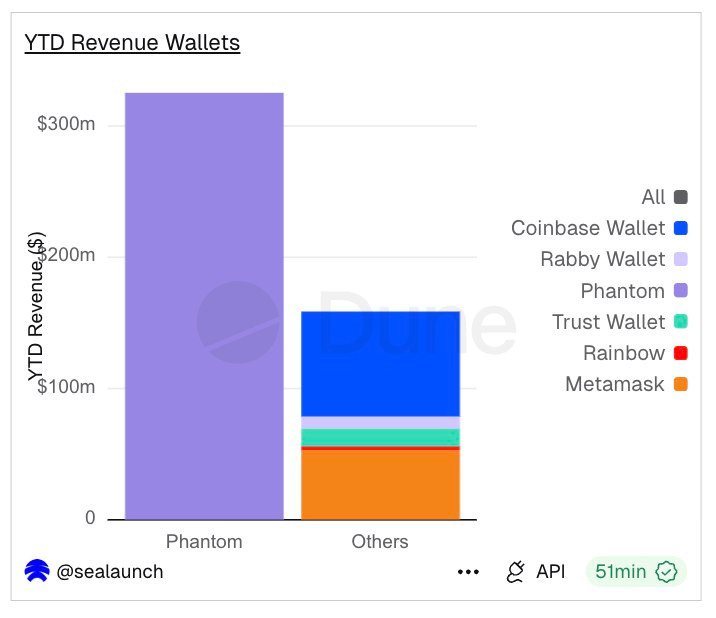
In 2025, Phantom generated more revenue than other DeFi wallets.
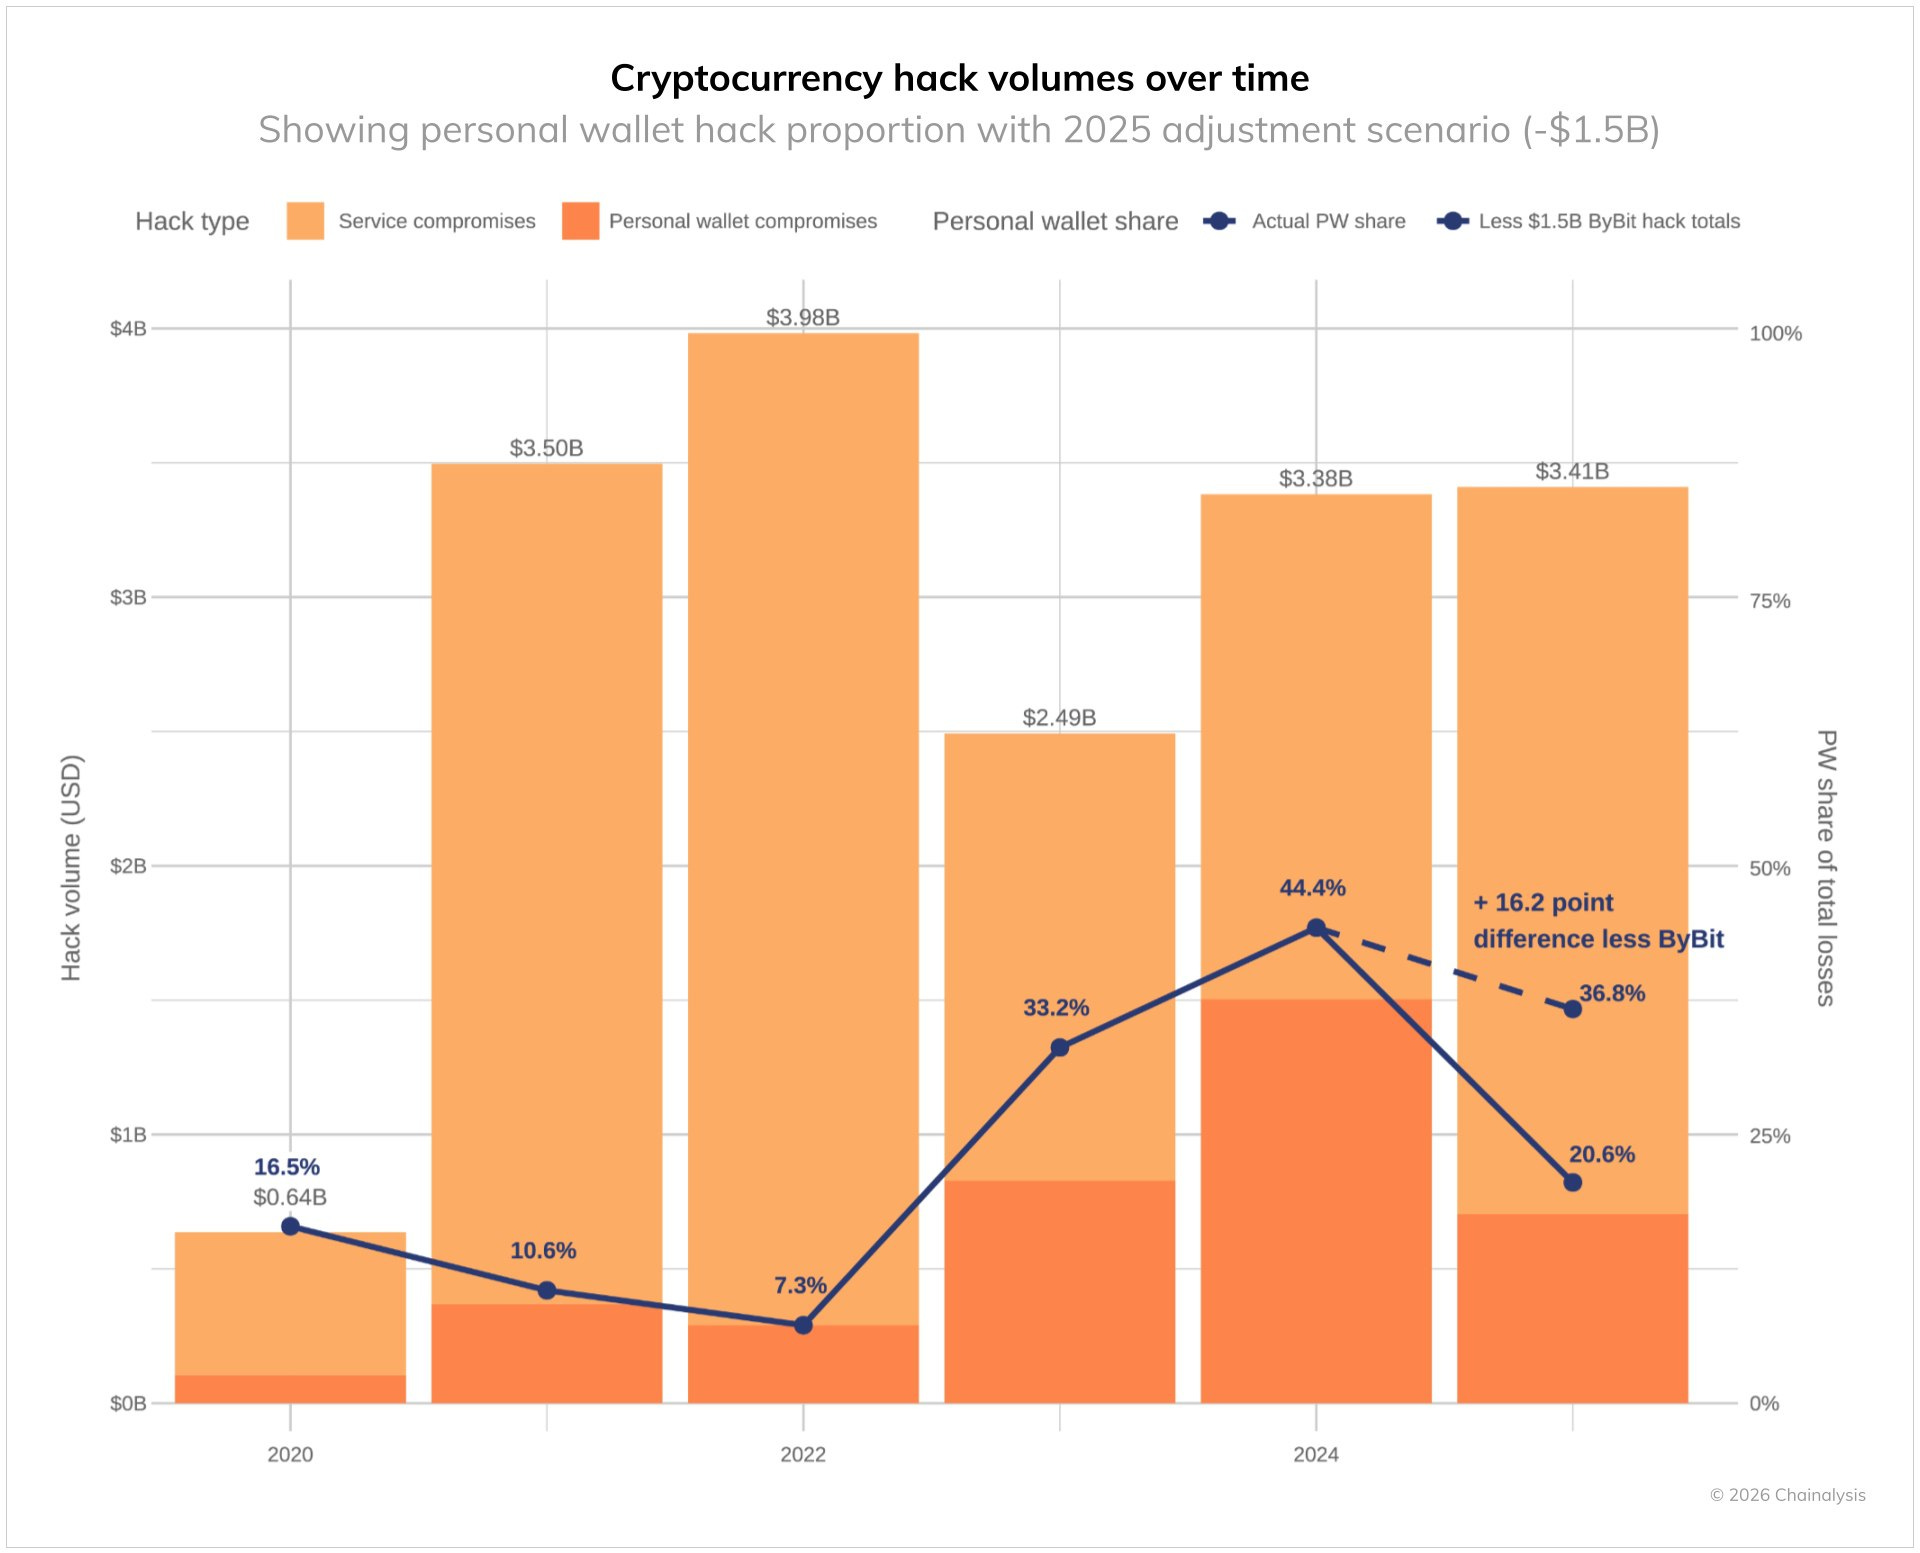
The cryptocurrency industry witnessed over $3.4B in theft from January through early December 2025, with the February compromise of Bybit alone accounting for $1.5B of that total. Personal wallet compromises have grown substantially, increasing from just 7.3% of total stolen value in 2022 to 44% in 2024. In 2025, the share would have been 37% if it weren’t for the outsized impact of the Bybit attack
Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Crypto Digital Assets Vice President at Goldman Sachs
Product Manager Consumer Trading at Kraken
VP - Digital Assets Product Strategy & Commercialisation at BNY Mellon
Senior Manager, Growth Products – Crypto Initiatives at Visa
Associate, Marketing at Gemini
Senior Repo and Lending Trader - Digital Assets at Keyrock
Business Development Manager VIP Partnerships at Crypto.com
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.
great to see a new report this year 🚀
🤝