

We’re back after a 2 week summer break. Welcome to the new subscribers that have joined us over the last couple of weeks. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: Stripe and Paradigm launch Tempo, Bitcoin treasury company Treasury B.V raises $147m.
Institutional Corner: SEC and CFTC issue a joint statement on crypto, UK’s HM Treasury releases a draft update to UK money laundering regulations, South
Korea publishes a new guideline on crypto lending services for centralised trading platforms.
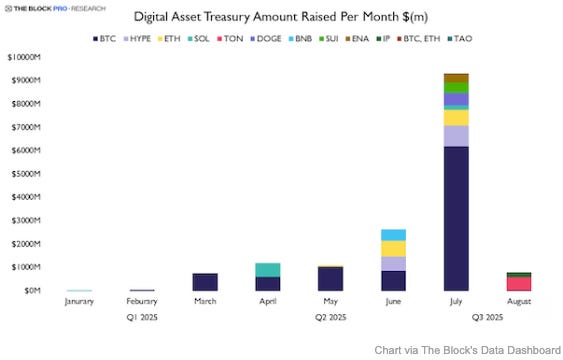
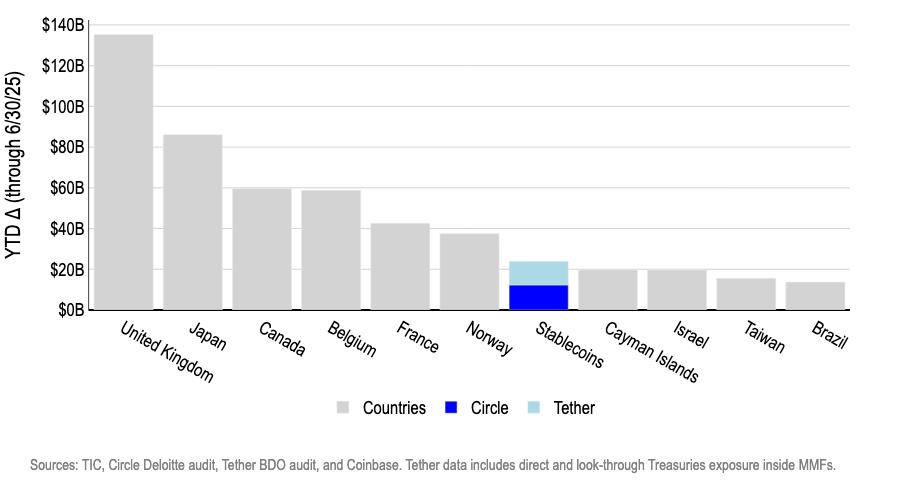
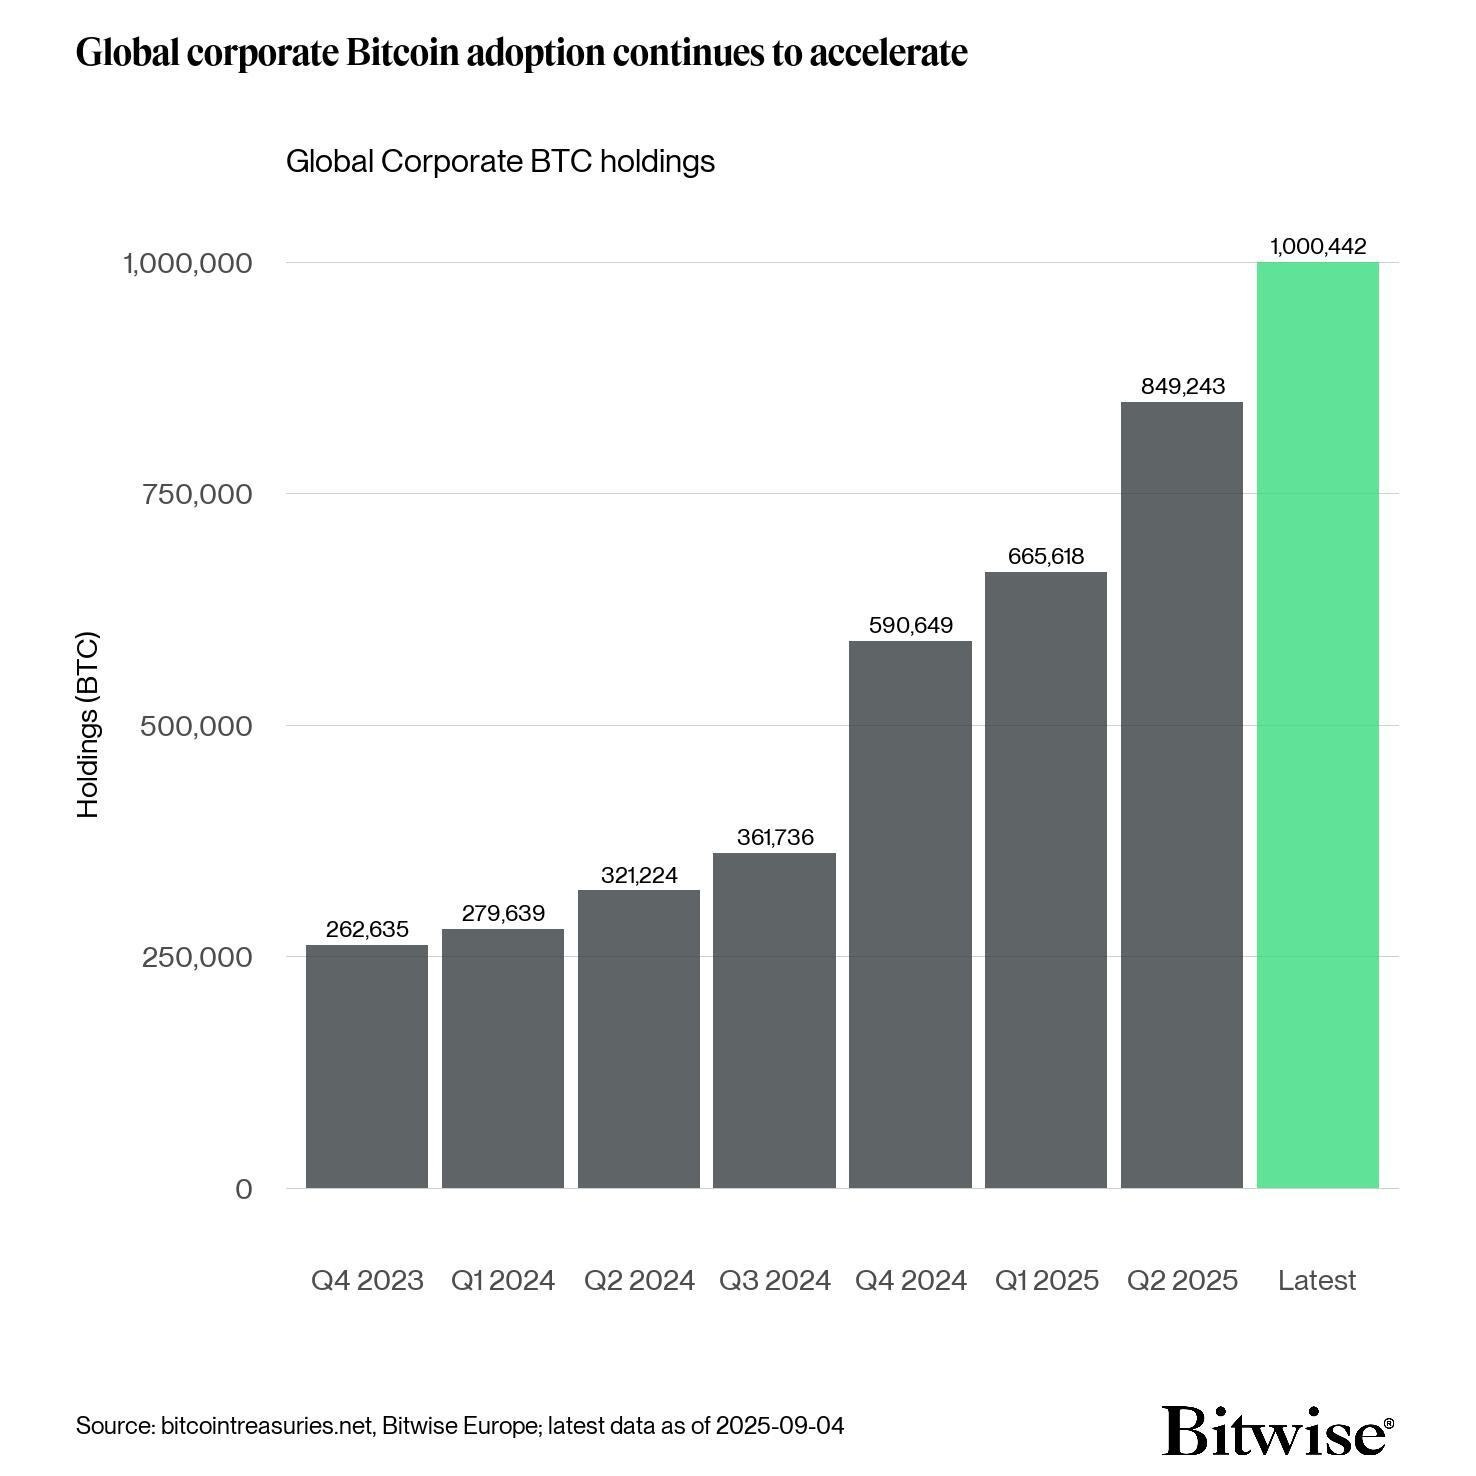
Charts of the Week: Digital assert treasuries the dominant force in crypto capital allocation this year, the top 2 stablecoin issuers the 7th largest buyer of treasuries this year, global corporate BTC holdings crosses 1m BTC.
Top Jobs in Crypto: Featuring Elliptic, Gravity Team, Wintermute, Crypto.com, Blockchain.com, Avenir Group, LMAX.
Macro Update
This is where we connect the dots between macro and crypto.
A Beautiful Debasement
As Connecting the Dots makes its return from a well earned summer break, so too does the volatility lull in crypto appear to be coming to an end.
Debt sustainability fears in Europe were the protagonist for an early week sell off in risk which saw BTC trade to lows sub $108k. Political turmoil in France acted as the catalyst, sparking a bond sell off which saw French and UK yields hit some of their highest levels in nearly 3 decades.
French Prime Minister Francois Bayrou was forced to call for a confidence vote due on September 8th as he seeks parliamentary approval for his government's unpopular, austerity budget which aims to cut EUR 44bn in spending and includes controversial measures such as removing two bank holidays. Sacre bleu!
The likely loss of this confidence vote will consequently lead to his resignation and force President Macron to appoint a new prime minister - potentially from the centre left - or dissolve parliament for early elections.
Either way, this political stalemate and reluctance to get a spiralling deficit (which has seen debt soar to 114% of GDP and the deficit of around 6%, well above the EU’s 3% ceiling) under control triggered an already nervous bond market, which has seen steadily climbing “term premia” (the extra yield investors demand for holding longer dated debt).
Unsustainable Deficits…
All of this goes to re-iterate the point we made in our last episode of Connecting the Dots. The current fiat, debt based system is unsustainable and depends on an ever expanding money supply and central bank driven liquidity, with fiat currency the ultimate escape valve.
Nothing can stop this train and the deterioration in public finances is being exacerbated by high nominal rates (Bessent and Trump aren’t even trying to hide the reason that they want the Fed to cut rates is to help temper the spiralling deficit by reducing interest costs.) It is also compounded by a rising “debt intensity” of growth. That is, it requires increasing units of debt to produce one unit of growth. Sustaining current levels of growth therefore necessarily requires increasing amounts of debt.
No President or leader can reduce the deficit without accepting substantially lower rates of growth which with only 4-5 year terms no one is incentivised to do.
We’ve seen the Labour government in the UK come in promising to get the deficit under control, only to subsequently increase spending and turn a £20bn "black hole” into a £50bn black hole in the space of a year.
Bessent came in promising to return fiscal deficits to 3%, but has quickly reneged and now, continuing to run deficits north of 6%, is relying on the miracle of growth to help bring the deficit back into balance.
We’re therefore at the stage where fiscal needs to run hot but also be accompanied by easy monetary policy (albeit in the form of lower rates and/or ever increasing liquidity) to stop the entire system from collapsing.
In need of a reset….
The whole system needs some form of reset or debt jubilee. They managed that with ZIRP (Zero Interest Rate Policy) post 2008, but Covid induced inflation has messed that up. They therefore need to get creative with financial repression, as the US has been doing with their “treasury QE” - front loading the debt issuance at the short end of the curve to keep longer term yields under control in a pseudo form of Yield Curve Control. Default comes via the stealth debasement of fiat currency.
In a best case scenario, major governments and central banks will be able to maintain sufficient confidence and market credibility that this debasement happens slowly without anyone really noticing.
To paraphrase Ray Dalio, a "beautiful debasement”
In a worst case scenario, markets lose all confidence and there’s a speculative attack on bond markets and a consequent currency crisis resulting in an “ugly debasement.”
In a beautiful debasement scenario, Bitcoin goes to $1mio over the space of 3-5 years. In an ugly debasement scenario, Bitcoin goes to $1mio overnight!
The bond market then is perhaps the most important market to monitor right now. Soft data eased some of the bond market pressures towards the end of the week, but the underlying issues and spiralling debt dynamics are not going anywhere!
Labour market weakness…
On the data front, the US labour market was keenly in focus with several reports painting a rather bleak picture of weakness, highlighted by Friday’s Non Farm Payrolls which came in at a paltry 22k, down from July’s revised 79k and below estimates of 77k. June’s numbers were also further revised down from +14k to a loss of 13k jobs. If JPow had the real numbers to hand in July, surely he would have cut?
The unemployment rate also ticked higher to 4.3%, its highest since 2021, whilst earlier in the week, the JOLTS survey showed job openings falling to the lowest level since Sep 2024 at 7.18mio whilst the number of unemployed Americans exceeded the number of job openings for the first time since 2021.
Markets are consequently pricing 100% chance of a September cut and even a circa 10% probability of a 50bp cut. Maybe “Too Late JPow” has indeed left things a little “too late” 😬
Powerful tailwinds…
Whilst this softness has reignited some recession fears, we remain however of the view that we’re in somewhat of a goldilocks environment characterised by slowing, not collapsing growth and sticky, not accelerating inflation, all of which allows rates to continue to come lower and liquidity conditions ease which will continue to support risk.
Indeed, the Services ISM came in at a stronger 52.0, up from 50.1 with new orders expanding at a healthy 56.0. Prices paid also softened a touch to 69.2 down from 69.9. Growth therefore remains resilient, inflation not showing material signs of acceleration. The labour market signals are also “murkier” than usual given the change in the supply dynamics with Trump’s clampdown on immigration. One would therefore expect the number of new jobs to fall, but equally the economy doesn’t require as many jobs with reduced labour supply.
So whilst the macro doomers want to re-price recession risk, we remain somewhat sanguine here. In fact, what stood out to us last week was the resilience in the US bond market, despite the bond turmoil in Europe. US 10yr yields post the soft job numbers broke to the lowest levels since early April. This has consequently re-asserted pressure on the dollar which continues in a downtrend. Combined with oil also breaking down again amidst another looming OPEC+ production increase, this all represents another substantial easing in global liquidity and financial conditions and forms a powerful tailwind for risk.
Interesting to us also, despite markets pricing more aggressive rate cuts from the Fed, US 5yr breakevens (a measure of expected inflation over 5 years) moved lower, which suggests the market on Friday did not move to price in the more risk negative “stagflation” scenario.
This market loves to build “walls of worry” which we typically climb so long as liquidity keeps rising and financial conditions are easing. This is particularly the case when the market remains underweight risk, as we believe it currently is. The above cross-asset dynamics are reflexively powerful counters to those wanting to sell risk on recession fears.
For all the bearish hopes of the weak September seasonality, US equities have continued to make new highs. Bitcoin is clearly digesting some supply and consolidating, but with gold making new record highs, reflecting the ongoing debasement as fiscal runs hot and bond markets financially repressed, if equities and risk continue to climb the wall of worry (we think they will) Bitcoin will be free to catch up with gold.
Bull market still on 💪
Native News
Key news from the crypto native space this week.
Stripe and Paradigm have launched Tempo, a new blockchain platform designed for stablecoin payments and real-world transactions. Tempo aims to optimise stablecoin transactions by offering high-speed processing, low fees, and scalability, supporting over 100,000 transactions per second. The platform is built with input from major companies like OpenAI, Visa, and Shopify, and is focused on enabling various use cases such as global payments, payroll, and remittances. Tempo operates independently with its own full-time team while maintaining connections to both Stripe and Paradigm, blending Stripe's payment expertise with Paradigm's blockchain technology. Read the full press release from Paradigm HERE.
Bitcoin treasury company Treasury B.V. said it had raised initial funding of €126 million ($147 million) through a private round led by the venture capital firm of billionaires Cameron and Tyler Winklevoss. Funding was also supported by Nakamoto Holdings Inc., a Bitcoin treasury company that merged with New York-listed healthcare services firm Kindly MD Inc. earlier this year. Other investors included UTXO Management, Off the Chain Capital, M1 Capital and Mythos Venture Partner. Treasury plans to pursue a reverse listing on Euronext Amsterdam through MKB Nedsense N.V., according to the statement. Upon completion of the transaction, Treasury is expected to trade under the ticker TRSR.
Institutional Corner
Top stories from the big institutions
The U.S. SEC and CFTC issued a joint statement on crypto this week. The SEC’s Division of Trading and Markets and the CFTC’s Division of Market Oversight and Division of Clearing and Risk are announcing a cross-agency initiative in furtherance of the SEC’s Project Crypto and the CFTC’s Crypto Sprint to coordinate efforts regarding the process for enabling the trading of certain spot crypto asset products. The statement did not mention specific digital assets, but said their joint staff statement covers crypto products centred on "leverage, margin, and financed spot retail commodity transactions.” Exchanges registered with the U.S. Securities and Exchange Commission and the Commodity Futures Trading Commission should be allowed to facilitate trading of some spot crypto products. Read the full statement HERE.
HM Treasury in the UK released a draft of proposed changes to current money laundering regulations this week that address loopholes and evolving risks, including stricter requirements for crypto businesses. According to the update “The updates aim to deliver a more risk-based, proportionate regime that is robust against financial crime whilst remaining workable for industry. The government has also committed to improve sectoral guidance on AML/CTF compliance on a range of issues, and to publish separate guidance on the use of digital identity verification for AML/CTF purposes.” The release follows a public consultation in 2024, which highlighted weaknesses in the UK’s regime linked to pooled client accounts, trust registration, crypto business oversight and challenges in customer due diligence. The new draft regulations propose several changes for crypto firms. The Financial Conduct Authority will apply a broader “fit and proper” test to firm controllers, replacing the current beneficial owner test, to ensure oversight captures complex ownership structures. Other provisions will lower the threshold for change-in-control notifications from 25% to 10%, aligning with the Financial Services and Markets Act (FSMA) regime. Read the full draft policy document HERE.
South Korea's Financial Services Commission published a new guideline on crypto lending services for centralised trading platforms on Friday. The new rules prohibit leveraged lending that exceeds the value of collateral, and set an interest rate cap of 20%. They also restrict products that require users to repay with cash instead of crypto, as this is considered a violation of credit business regulations. The guidelines add that companies offering these services must use their own capital and are prohibited from circumventing the rules through third-party services. The guideline also stipulates that lending services are limited to the top 20 cryptocurrencies by market capitalisation, or cryptocurrencies that are traded on three or more licensed local exchanges.
Charts of the Week
Because charts are just as important as macro.
Digital asset treasury (DAT) investments have emerged as the dominant force in crypto capital allocation this year, with companies raising over $15 billion through August. Hat tip to The Block for the chart.
The top two stablecoin issuers have been the seventh largest buyers of US treasuries in 2025 YTD.
Global corporate Bitcoin holdings has crossed 1 million BTC for the first time ever. Hat tip to Bitwise for the chart.
Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Cryptocurrency Intelligence Analyst at Elliptic
Algorithmic Forex and Crypto Trader at Gravity Team
Graduate DeFi Algorithmic Trader at Wintermute
Blockchain Security Technical Support Engineer at Crypto.com
UK Market Lead at Blockchain.com
Options Trader at Avenir Group
Broker Operations Associate at LMAX
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.
good to have you back! great one. thanks
Great insights!