

Welcome to the new subscribers that have joined us over the last week. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: Apollo and Securitize rolling out tokenised investment opportunities, Tether reports record breaking profits, Tuttle Capital proposed a number of new crypto ETF’s.
Institutional Corner: Staking no longer be deemed a collective investment scheme in the UK, El Salvador amends its Bitcoin law.
Charts of the Week: Crypto.com US market share grown significantly, Ethereum Layer 2s have reached an all-time high in throughput, Crypto wallet users hit an all time high.
Top Jobs in Crypto: Featuring Polygon Labs, Kraken, Bitpanda Pro, Crypto.com, Ripple, Trireme.
Macro Update
This is where we connect the dots between macro and crypto.
Taxing Times
A big macro week was somewhat overshadowed by an early week tech driven sell-off, in response to the emergence of DeepSeek, a Chinese artificial intelligence (AI) company who have released a new open source large language model. DeepSeek reportedly requires much less energy and computer processing power than other competitors such as OpenAI. With obvious implications for NVIDIA, the dominant provider of the expensive GPU’s, NVIDIA’s shares were hit hard on Monday, down 17%, along with other MAG7 who were thought to be developing a moat around AI, given the assumed high costs of compute.
As the week wore on, some scepticism emerged over the true costs to develop DeepSeek, with suggestions the firm likely had access to more high powered chips and funding than had been disclosed, including access to NVIDIA’s H100’s which it could not reveal due to US export controls. Several positive earnings surprises and upbeat forward guidance, notably from Apple and META also aided the recovery, with the Nasdaq finishing a little over 1% lower.
Whilst there are better tech brains than ours to comment on the implications of DeepSeek, the cheaper it becomes to run AI, the more aggregate demand there will be for compute, benefitting the broader tech space. From a macro point of view, this further reinforces our disinflationary view of the world which we laid out a couple of weeks ago, that will help rates continue the path lower. Also, as it relates to crypto, crypto is the currency of AI, facilitating transactions in an increasingly decentralised, automated world 🔥
Fed nothingburger…
On the macro, the Fed held rates steady this week as expected, re-emphasising the view that the committee "does not need to be in a hurry to adjust its policy stance” and reinforced the data dependency, requiring continued progress on inflation or weakness in the labour market before making another rate cut. Inflation is currently viewed as being “somewhat elevated” but JPow expressed some confidence that inflation would continue its path lower with policy still seen as “restrictive.” Net, we learnt nothing new from this FOMC.
Supporting the Fed’s view of inflation remaining “elevated,” its preferred measure of inflation, Core PCE came in flat at 2.8% YoY for a 3rd month in a row, although it dampens the fears that inflation is re-accelerating. As we continue to believe, this is the “bumpy” part of the disinflationary process which we believe will continue the path lower over the coming months as services inflation “catches down” to manufacturing prices. Indeed, 3 and 6 month core PCE is running below 12 month measures and points to core PCE resuming the path lower from here.
Meanwhile, Q4 data in the employment cost index (ECI), as highlighted by the Fed whisperer Nick Timiraos, shows a cooling labor market with wages and salaries for private sector workers, ex-incentive paid occupations, rising at the lowest since 2021 at 3.8%. The QoQ increase is at the mildest since Q4 2020. As JPow himself noted on Wednesday, the labour market is currently not a source of inflation.
Easing rates and liquidity regime…
Elsewhere, the ECB cut rates 25bps to 2.75% as expected, with ECB President Lagarde noting the disinflation process was “well on track” and described policy as “still restrictive" without indicating how much further they would likely need to go. With the Eurozone's two largest economies, German and France, being shown to have both contracted in Q4 amidst a continued global manufacturing recession, we expect those rate cuts have much further to go✂️
Also in the eye of the global manufacturing recession storm, the Bank of Canada cut rates 25bps to 3%, the 6th cut in a row. Interestingly, the BoC also ended quantitative tightening and will start buying assets again as part of the “business-as-usual balance sheet management process”
We continue to be in an easier global rates and liquidity regime which will continue to power this crypto bull market 🚀
Taxing times…
If DeepSeek overshadowed the macro last week however, going into this week risk looks set to be rocked by Trump’s announcements that he will impose, starting Tuesday, 25% tariffs on imports from Canada and Mexico and 10% on Chinese goods. Canadian energy faces a lower 10% tariff. The reaction over the weekend is that Canada, Mexico and China will also prepare retaliatory tariffs. Bitcoin as the only risk market open consequently getting hit back below $100k.
The kneejerk reaction to renewed trade wars will of course be a stronger dollar and higher global yields as markets focus on the potential inflationary impact. Although, given an already weak global growth outlook, we suspect the inflation impact to be much less than the global growth impact which actually continues to feed a bullish bond view.
This is very much the Trump playbook however, to go big to focus minds and get people around the negotiating table. Trump is using tariffs to shock Canada and Mexico into taking action on drug trafficking and border security. We wouldn’t be surprised to see a tweet from Trump claiming to have had a “great and perfect” phone call with Canada and Mexico that turns this around by midweek!
Short term, expect a volatile start to the week for Bitcoin, trading in line with broader risk. Ironically however, this only reinforces the longer term bull case for Bitcoin as a decentralised, borderless, non sovereign asset and consequently as the ultimate hedge against the failure and disruption of existing economic and political structures. Strap in for a difficult week, but keep stacking. The macro remains on course and will ultimately continue to power this bull run 💪
Native News
Key news from the crypto native space this week.
Apollo Global Management and Securitize (backed by BlackRock) have begun rolling out tokenised investment opportunities. Their first venture involves providing tokenised access to Apollo Diversified Credit Fund. Access to the Apollo Diversified Credit Securitize Fund (ACRED) will "initially be available on the Aptos, Avalanche, Ethereum, Ink, Polygon, and Solana," the announcement said. Wormhole will allow for tokens to move across the different available blockchains. Apollo Partner Christine Moy said in an X post "We want crypto DeFi to expand access to institutional-quality products. With 11.7% returns in 2024, ACRED offers today’s generation crypto-native investors a gateway to private credit markets." Moy added that for investors "building a diversified portfolio on-chain, this offers a higher-yielding complement to stablecoins and tokenised treasuries—plus a diversifier to volatile crypto-native yield products. It’s a key piece for a balanced, on-chain portfolio." Read the full announcement HERE.
Tether, the crypto company behind the largest stablecoin USDT, said on Friday it generated $13 billion group-wide net profits last year in a record-breaking year. $7 billion of the profits derived from the firm's vast U.S. Treasuries and repo holdings, and $5 billion from unrealised appreciation of the company's gold and bitcoin holdings. Other investments contributed $1 billion. According to the company's latest quarterly attestation signed by accounting firm BDO Italy, the group's stablecoin issuer arms Tether International Limited and Tether Limited disclosed $143.7 billion of assets in reserve against $136.6 billion in liabilities, adding up to $7 billion of excess reserves backing its stablecoins. Read the full announcement from Tether HERE.
ETF issuers are really starting to test the water on what the SEC will allow in crypto ETF’s. Tuttle Capital Management is testing the waters by proposing the first-ever exchange-traded funds tied to Chainlink (LINK), Cardano (ADA), and Polkadot (DOT). Among the 10 proposed leveraged ETFs is the first-ever ETF tied to the Melania meme coin (MELANIA), along with leveraged products for XRP (XRP), Bonk (BONK), BNP, Solana (SOL), Litecoin (LTC), and the meme coin tied to U.S. President Donald Trump (TRUMP). See the full filing HERE.
Institutional Corner
Top stories from the big institutions
Following a regulatory amendment by the UK Treasury on Friday, the act of locking up tokens to earn rewards (staking), will no longer be deemed a collective investment scheme in the UK. The change exempts staking from the large regulatory burden usually required of such schemes. It also brings clarity for crypto firms, exchanges, and DeFi protocols that offer staking services. As a reminder, the government said it aims to engage firms on draft legal provisions for crypto regulations, including stablecoins, in early 2025. See the full staking legislation HERE.
According to news reports this week, El Salvador’s Congress has reportedly approved legislation to amend its Bitcoin laws to comply with a deal struck with the International Monetary Fund to adjust its exposure to crypto. The bill was ratified by the country’s Legislative Assembly just minutes after President Nayib Bukele sent in the legislation. El Salvador struck a $1.4 billion loan deal with the IMF in December, with the agency requiring the Bukele’s government to scale back its involvement in Bitcoin and make BTC optional and voluntary for private sector merchants. The reform was passed with 55 votes in favor and only two against. Previously, it was a legal requirement for businesses to accept Bitcoin as payment.
Charts of the Week
Because charts are just as important as macro.
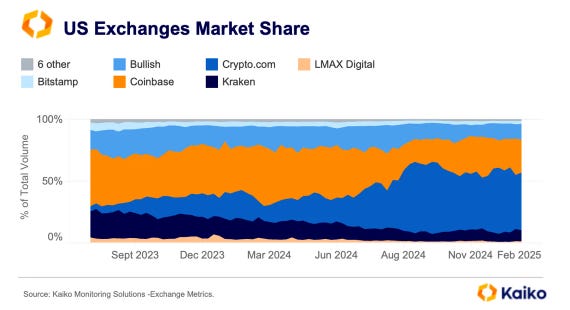
Crypto.com has taken the U.S. market by storm, with its market share surging from 4% in 2023 to 47% as of last week. In contrast, Kraken and Coinbase have been the biggest losers, with Kraken’s share more than halving from 21% to 9%, and Coinbase’s declining from 45% to 27% over the same period. Hat tip to Kaiko data for the chart.
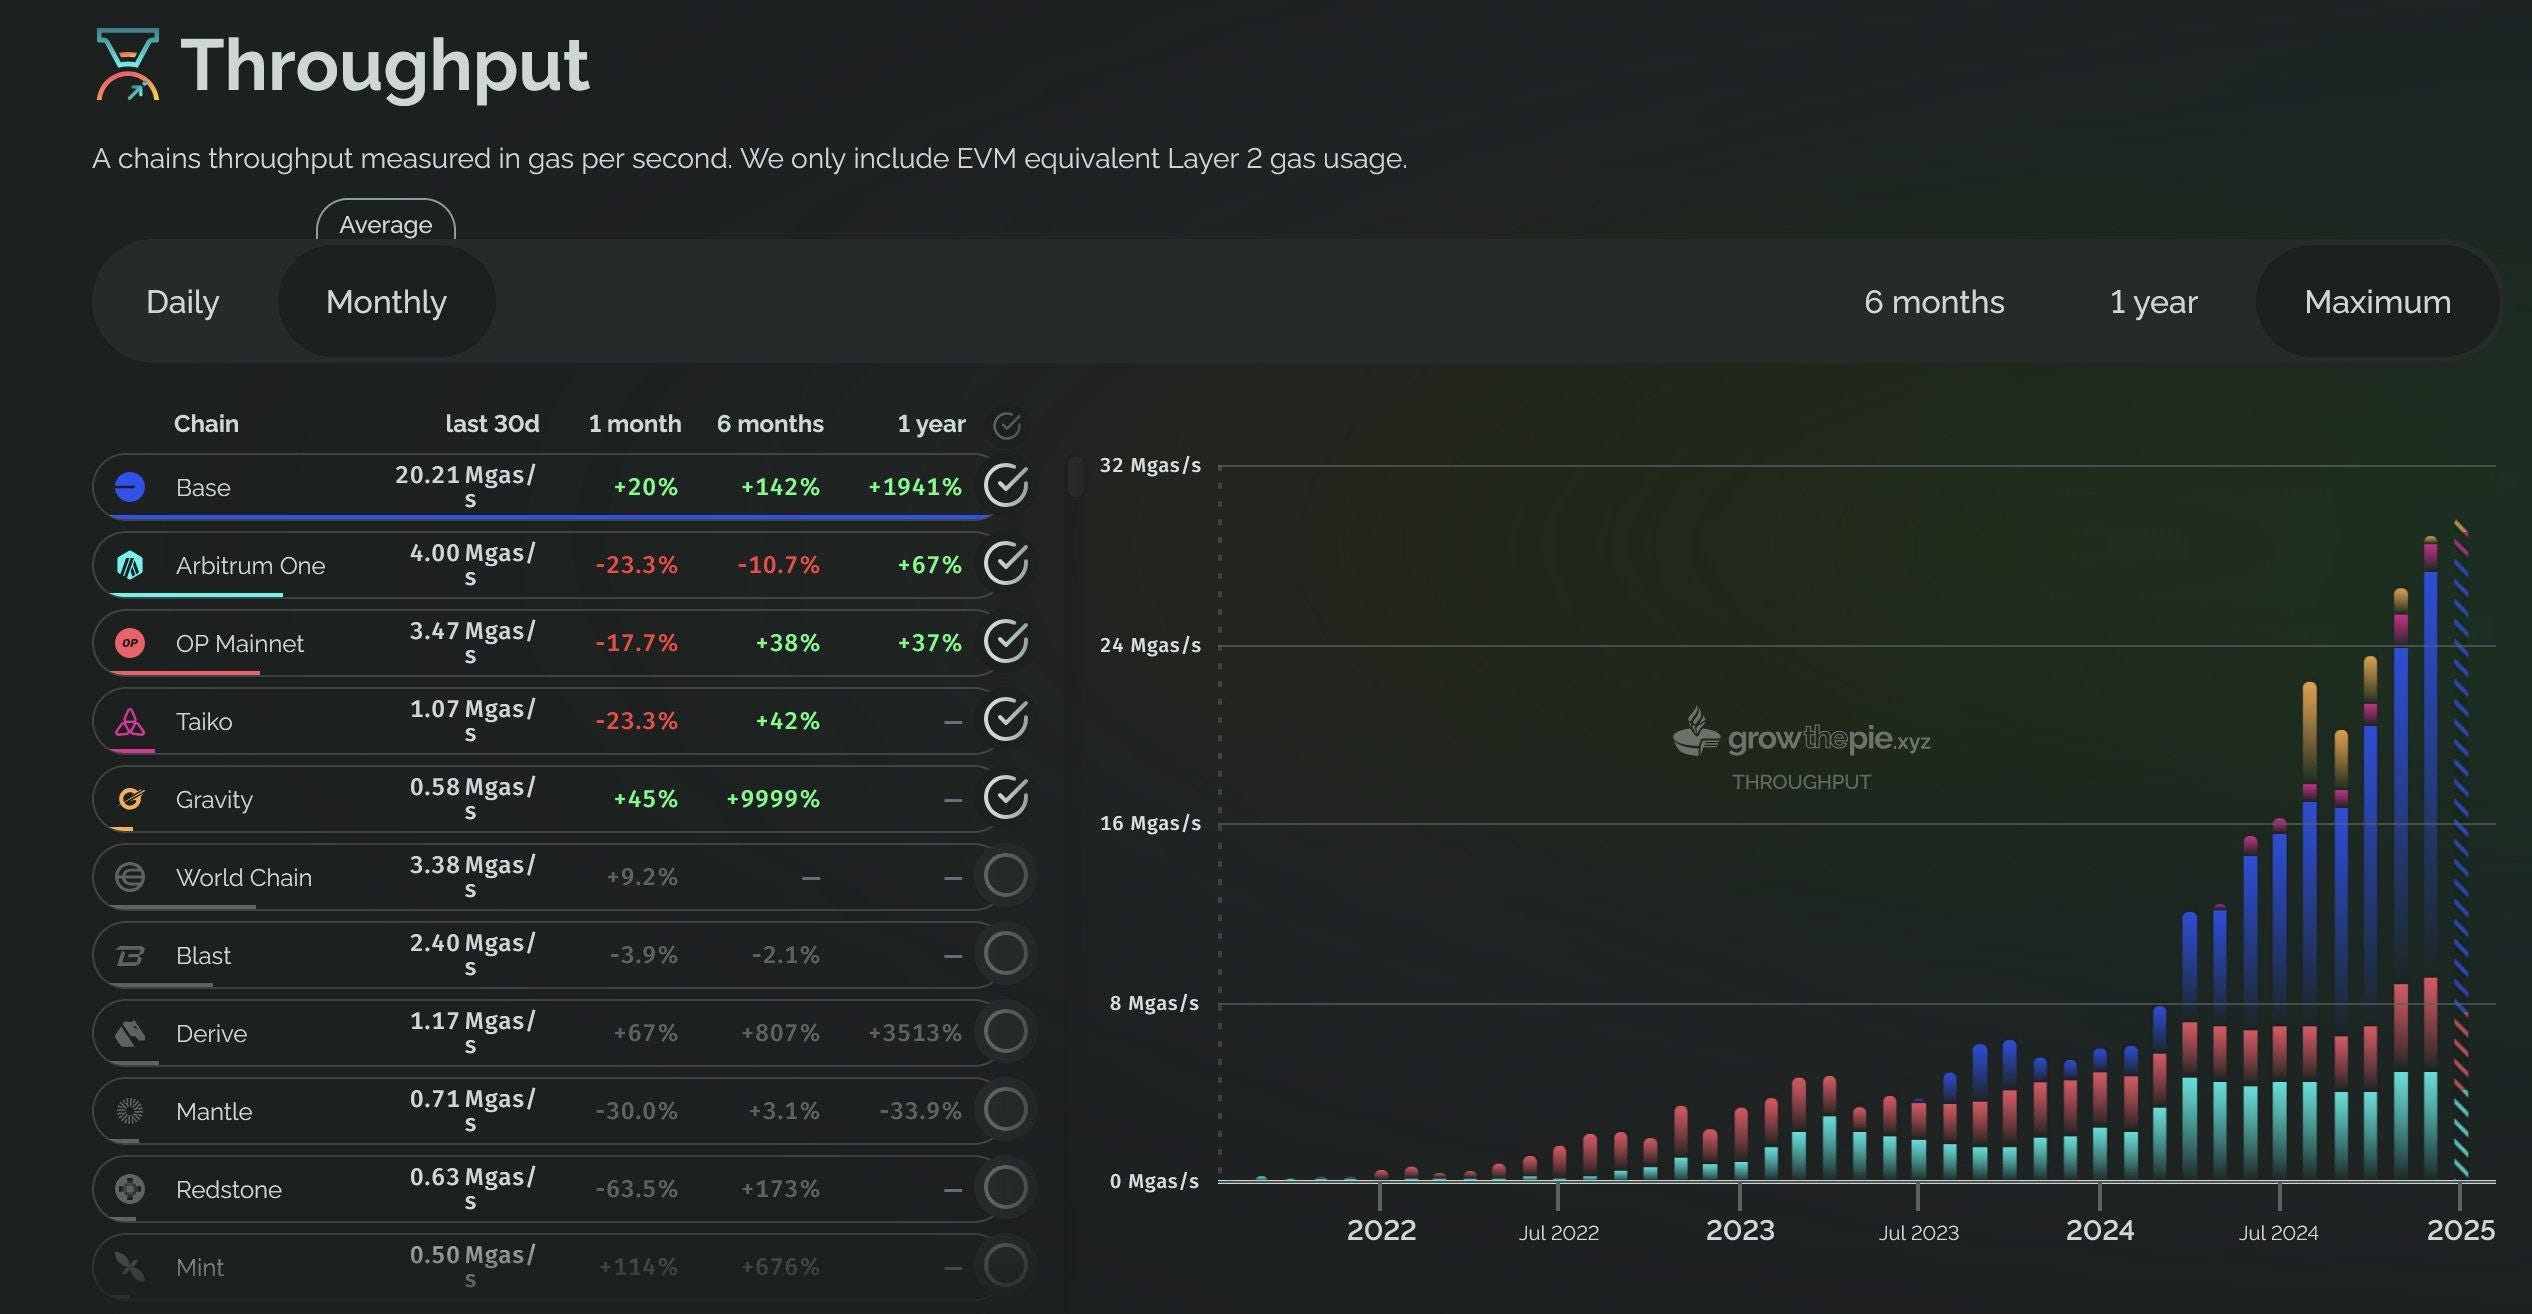
Ethereum Layer 2s have reached an all-time high in throughput with Base leading the way.
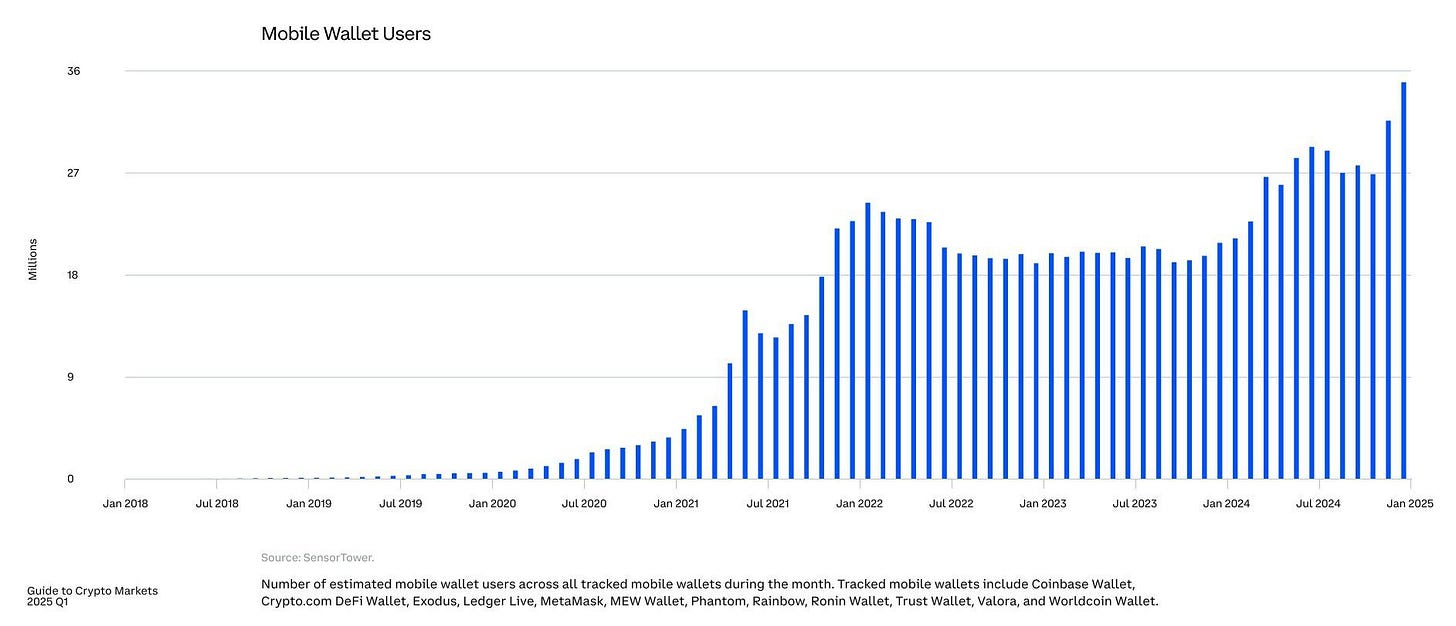
Crypto wallet users hit an all-time high of 36 million in Q4, 2024.
Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Business Development Manager - Payments at Polygon Labs
Kraken Institutional - Sales Manager UK
Country Lead Broker UK at Bitpanda Pro
Senior Onchain Partnership Manager at Crypto.com
Markets and Trading Intern Summer 2025 at Ripple
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.