

Thank you for the support in 2025. We hope you have a great Christmas and New Year, best of luck for 2026!
Welcome to the new subscribers that have joined us in the last week. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: Crypto thefts slightly higher this year, Coinbase announces an expansion to its product suite, Coibase to acquire The Clearing Company.
Institutional Corner: Mike Selig to lead the CFTC, JPM cautious on stablecoin growth.
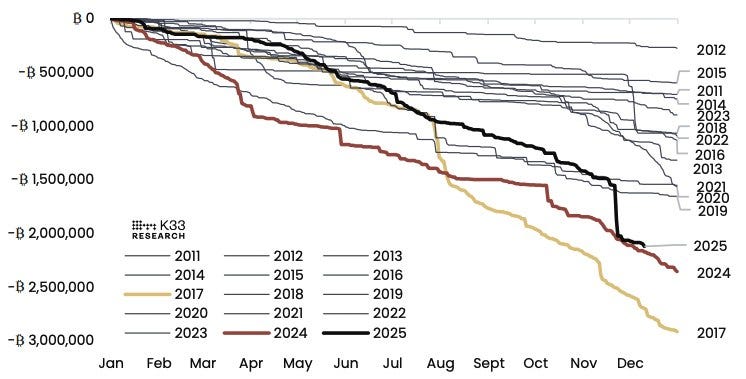
Charts of the Week: 2024 and 2025 is the second and third-largest years for long-term supply reactivation, Gold backed stablecoins now exceed $4 billion in market cap
Top Jobs in Crypto: Featuring BlackRock, SSV Labs, Robinhood, Sokin, CoinMarketCap, Galaxy, Keyrock, Uphold.
Macro Update
This is where we connect the dots between macro and crypto.
Liquidity Games
Choppy markets as we wind down into the holiday season, where year end adjustments and PnL management considerations dominate anything more fundamental.
Whilst our “Goldilocks” thematic - slowing not collapsing US growth, with sticky, not accelerating inflation amidst a global rate cutting cycle and rising global liquidity - has played out well and driven solid returns across equities and precious metals, Bitcoin and the broader crypto space has endured a disappointing year.
Despite all of the positive idiosyncratic drivers for Bitcoin, with the progress of a supportive US administration reinforcing the institutional adoption story, and despite making record highs above $126k in early October, Bitcoin as we write, is down circa 5% YTD Vs the USD and ~40% Vs gold 😬
Bitcoin’s underperformance
It’s difficult to pinpoint a single driver, but a large part of Bitcoin’s underperformance this year can be explained by persistent, mechanical supply. We’ve seen substantial selling from long-term “OG” holders who, having held through multiple cycles, began distributing aggressively around the psychologically important $100k level. That supply has been steady and price-insensitive, weighing on the market despite otherwise supportive fundamentals.
At the same time, reflexive belief in the “four-year cycle” has encouraged further distribution, while the broader AI / high-beta tech trade has begun to roll over as investors question the sustainability of capex and return expectations. In normal conditions, Bitcoin remains tightly correlated to these momentum-driven risk trades, amplifying downside when positioning unwinds.
October’s liquidation event added another layer. While the market de-levered with impressive speed — leaving Bitcoin only ~10% lower 24 hours later — there are credible indications that liquidity providers and market makers who absorbed the forced selling have since been gradually de-risking inventory, creating a persistent overhang into year-end. Combined with the capital destruction inflicted on leveraged speculators, demand has temporarily weakened just as supply peaked.
Crucially, many of these pressures appear transitory. Recent on-chain data suggests whale selling is slowing, with some large holders returning to net accumulation. If this mechanical supply overhang continues to ease, Bitcoin has significant scope to catch back up to its debasement cousin, gold.
US liquidity strangle
In terms of macro factors, Bitcoin remains ultra sensitive to liquidity. Whilst we continue to see measures of global liquidity rising - ever rising M2 money supply, tightening credit spreads, falling bond and equity volatility, weaker dollar, softer oil all contributing - US liquidity has been tightening.
We felt early in the year (outside of the Trump Tariff wobble) that the Goldilocks macro alongside rising liquidity would see a positive year for all risk assets. Underpinning this was the continuous draw down of the Fed’s Reverse Repo Facility (RRP) which has been a $2trn tsunami of cash flowing into this market 🌊
Once that hit zero, we felt there would be sufficient excess reserves in the banking system to keep flowing into the front end supporting treasury bill issuance and repo funding rates. Yet eventually, US funding liquidity would tighten and we’d potentially see a 2019 style “repo blow up”. That, in our view, would be where we would see a decent correction across equities and crypto.
In the event, the RRP effectively hit zero at the end of September - Bitcoin topped on the 6th October - and we’ve seen persistent underlying signs of stress in the repo funding market, including banks needing to tap the expensive Fed, Standing Repo Facility (SRF) at various times of stress.
Just don’t call it QE
Rather than the “blow up” we got a slow “liquidity strangle” which we feel Bitcoin has been hyper sensitive too. Somewhat surprisingly however, we’ve seen a very proactive Fed respond quite quickly to the stress, ending quantitative tightening (QT) and quickly followed by the recently announced balance sheet expansion via “Reserve Management Purchase (RMP)” - or as we like to call it, “not QE QE”. $40bn monthly purchases of T-bills.
Whilst the market “midcurvers” want to debate why it’s not QE - Ackchyually 🤓 - and it’s not in terms of its duration and stated intent, the key commonality remains: the Fed is creating money to buy Treasuries and, in effect, help fund the deficit.
When combined with the “Treasury QE” whereby Treasury Sec. Yellen, followed by Bessent focused the balance of treasury issuance to fund the ever growing deficit to the front end T-bills, reducing relative “back end” treasury supply, it begins to look and feel very much like QE. Adding to that, the changes to the Supplementary Leverage Ratio (SLR) which come into effect in Jan and will encourage banks to hold more longer dated treasuries, then the Treasury and the Fed are combining to deliver pseudo QE. Printing cash to fund the deficit at the front end, whilst anchoring yields in the longer end.
It’s “QE-lite” but will mean a slow and persistent debasement of the currency which will keep gold, equities and eventually Bitcoin trending higher over the next year. Indeed, JPow effectively has kept the RMP purchases open ended and will adjust to ensure abundant reserves remain in the banking system. Our guess is those purchases will need to step up, not down, as Mr Powell is hoping after a few months.
Either way, as was inevitable, the Fed are once again the liquidity providers - read “deficit funders” - of last resort and the brief hiatus for balance sheet expansion has ended. Equally predictable, the ability to “normalise” and reduce the size of the balance sheet, ended at a higher level than the previous QE funded peak. That is, the post-2008 QE saw the Fed balance sheet reach a peak of $4.5trn before falling back to $3.7trn under QT into the 2019 repo crisis before balance sheet expansion began again. This cycle, we saw a peak at $9trn before QT back to now $6.5trn where the US financial system started to fray and requires balance sheet expansion once again.
Nothing stops this train
This has been core to our “debasement trade” thesis that will drive Bitcoin and other hard assets higher forever. Namely the debt driven, fiat based system requires ever more debt and deficits to survive, requiring ever expanding central bank balance sheets to fund those deficits and provide liquidity to the market via money printing. Literally nothing stops this train 🚉
We’re seeing this play out acutely in Japan who are in the impossible position of needing to hike front end rates to stave off inflation, whilst also controlling a bond market which stands at circa 200% of GDP. JGB yields are now at levels last seen pre-2008, yet the currency is at its weakest levels Vs the USD in 35 years, after the Japanese asset bubble burst.
The reason the JPY is not strengthening is because contradicting the BoJ’s attempts to hike rates, they remain the marginal buyer of JGB’s, purchases of which need to be stepped up to “smooth” bond market volatility.
They are sacrificing the JPY to save the bond market. Whilst this threatens broader bond market volatility, contrary to the “macro doomers” incessant calls for a “reverse carry trade” with Japanese money being repatriated back home, money is flowing out of the country seeking relative safety elsewhere.
The BoJ can save the bond market or the JPY, they can’t save both. Inevitably, they will require the help and intervention of the US to supply more dollar liquidity and help keep a lid on USDJPY whilst the BoJ buys more bonds in an attempt to control the yield curve.
Japan isn’t the outlier, it’s the roadmap 👀
So as we get ready to explain to our families over the Christmas Turkey why “no lambo” this year, we feel into 2026 the liquidity games are going to step into overdrive as US and global debt is printed away. Combined with Trump and Bessent looking to juice the US economy into the midterms, 2026 likely runs very hot for all risk assets. Bitcoin will eventually catch fire and restore its place as the number 1 performing asset as it’s done 10 of the last 14 years.
Happy holidays to all of our readers. We look forward to sharing more thoughts in the new year 🎉
Native News
Key news from the crypto native space this week.
According to analysis from blockchain analytics firm Chainalysis, Cryptocurrency theft totalled over $3.41 billion from January through early December. The figure marks an increase from last year’s $3.38 billion. A single incident, the $1.5 billion hack of Bybit exchange accounted for around 44% of the annual total. The top three hacks represented 69% of all losses from services. Personal wallet compromises reached 158,000 cases involving at least 80,000 unique victims. The total value stolen from individuals declined to $713 million, down from $1.5 billion the previous year.
Coinbase announce an expansion to is product suite this week detailing plans for stock trading, prediction markets, an AI-powered financial advisor, and more. The announcements were billed as a major step in Coinbase’s effort to build an “everything exchange.” CEO Brian Armstrong said during a live-streamed event announcing the new products “Coinbase is no longer a place to just trade crypto, it’s a place where you can trade everything.” Beginning Wednesday, US users will be able to trade stocks and ETFs 24 hours a day, five days a week, in the Coinbase app alongside crypto, said Max Branzburg, the company’s head of consumer products.
Following that, Coinbase announced that it had agreed to acquire The Clearing Company, a prediction markets start-up that recently announced a $15 million seed round. The deal comes shortly after Coinbase began rolling out prediction markets on its platform last week, allowing users to trade on real-world outcomes such as elections, economic data, and sports within the same interface used for crypto, derivatives, and equities. The transaction is subject to customary closing conditions and is expected to close in January, Coinbase said. The Clearing Company was founded earlier this year by Toni Gemayel, a former head of growth at both Polymarket and Kalshi. The start-up raised a $15 million seed round in August from investors including Coinbase Ventures and set out to build an onchain, regulated prediction markets platform. Following the acquisition, The Clearing Company’s team will help Coinbase scale its own prediction markets product. The start-up employed around 10 people, and nearly the entire team is joining Coinbase as part of the deal
Institutional Corner
Top stories from the big institutions
On Thursday US Senators approved crypto ally Mike Selig to lead the Commodity Futures Trading Commission. Selig will replace interim CFTC Chairwoman Caroline Pham. On Wednesday, crypto payments firm Moonpay said it had hired Pham as its chief legal officer. A former partner at corporate law firm Willkie Farr & Gallagher, Selig has served as chief counsel at the Securities and Exchange Commission’s Crypto Task Force since March. He is also an advisor to SEC Chair Paul Atkins, who has committed to a pro-crypto agenda in an effort to bring equities markets onchain. Selig said in October, when he was nominated by President Donald Trump to lead the agency “I pledge to work tirelessly to facilitate Well-Functioning Commodity Markets, promote Freedom, Competition and Innovation, and help the President make the United States the Crypto Capital of the World.”
In their latest research report, JP Morgan analysts said that they do not expect the stablecoin market to reach a trillion-dollar scale over the next few years, arguing that growth is likely to track the broader crypto market rather than accelerate far beyond it. Their report noted that the stablecoin universe has expanded by about $100 billion this year to over $300 billion, with growth concentrated among the two largest coins. Tether’s USDT added around $48 billion in supply, while Circle’s USDC grew by about $34 billion, accounting for the majority of the increase. The analysts said this reinforces their long-held view that stablecoin growth is still driven mainly by activity within the crypto ecosystem. As a result, “the stablecoin universe is likely to continue to grow over the coming years broadly in line with the overall crypto market cap, perhaps reaching $500 billion–$600 billion by 2028, far lower than the most optimistic expectations of $2 trillion–$4 trillion.”
Charts of the Week
Because charts are just as important as macro.
2024 and 2025 is the second and third-largest years for long-term supply reactivation in Bitcoin's history, surpassed only by 2017.
Gold backed stablecoins now exceed $4 billion in market capitalization, having nearly tripled from $1.3 billion at the start of 2025.

Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Digital Assets Associate at BlackRock
Core Blockchain Team Lead at SSV Labs
Business Development Lead for Crypto at Robinhood
Product Manager for Stablecoins at Sokin
Senior Product Manager at CoinMarketCap
Vice President of Sales at GK8 by Galaxy
Product Manager for Trading at Keyrock
Business Development Lead at Uphold
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.
Nice write up thank you
Useful
https://organon.substack.com/p/the-nightmare-before-christmas-the-2fd?r=5rmgdf