

Welcome to the new subscribers that have joined us over the last week. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: Lido ETH staking at record low, Coinbase completes acquisition of Deribit, Mesh raises fresh capital, Bullish IPO’s this week.
Institutional Corner: Standard Chartered raises its ETH price targets, SEC pushes back its decisions on Solana ETF’s, Hong Kong SFC sets stricter custody requirements.
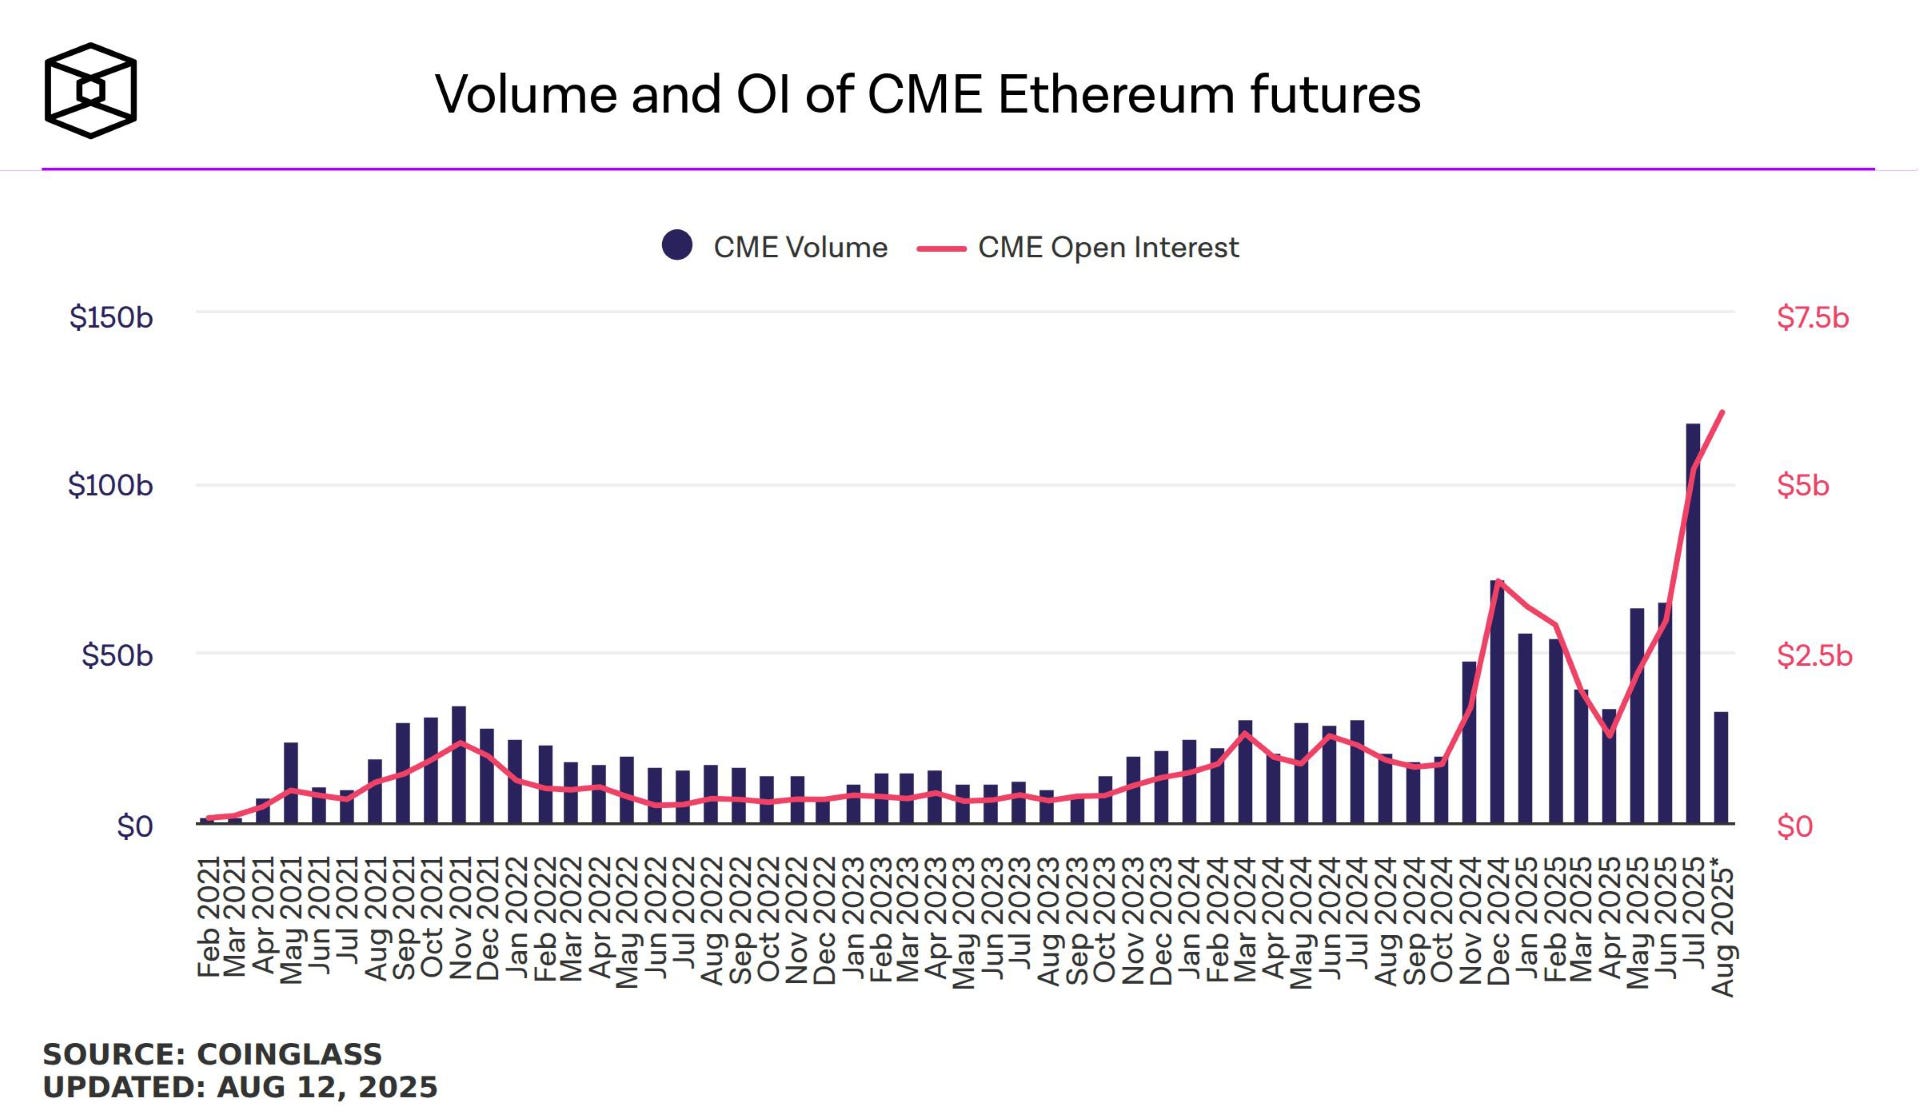
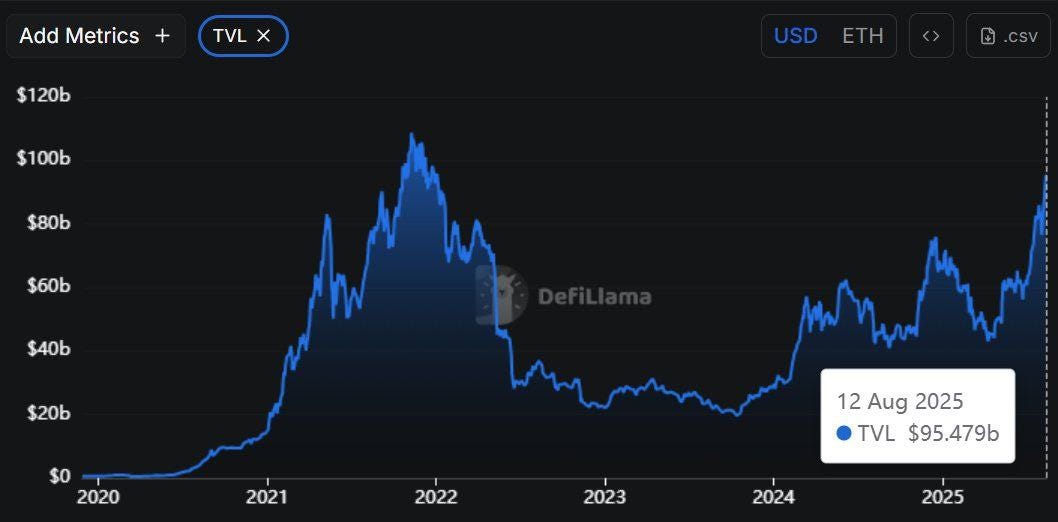
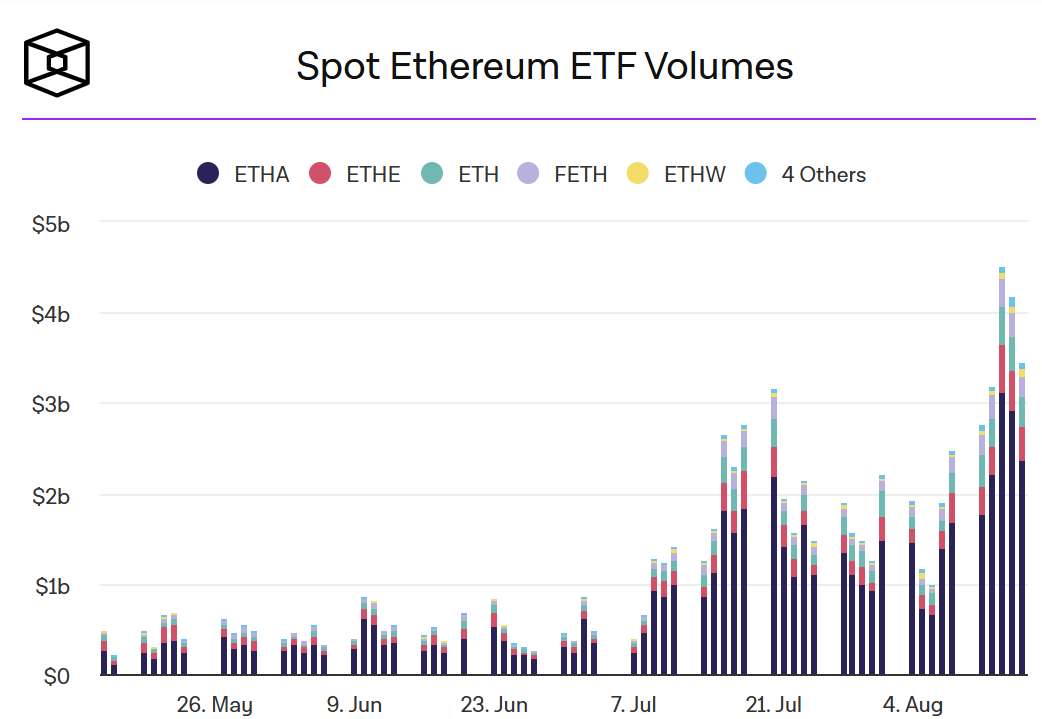
Charts of the Week: CME ETH futures volume hits record, TVL on ETH at highest level since 2021, ETH ETF volumes on the rise.
Top Jobs in Crypto: Featuring Kraken, the FCA, Ripple, Wintermute, Copper and BCB Group.
Macro Update
This is where we connect the dots between macro and crypto.
Fed QE is Coming
As the English Football Premier League kicks off this week, it’s perhaps apt to describe this week in crypto as a week, or game of two halves. Strong early gains saw Bitcoin clock new record highs and ETH just shy of visiting its 2021 highs, only to reverse into the latter stages of the week.
Driving these moves was the US data flow which was also a game of two halves. Tuesday’s CPI inflation report showed that headline inflation cooled modestly in July, with month-over-month inflation dropping to 0.2% from June’s reading of 0.3%, driven by declines in grocery and energy costs. This saw a flat YoY reading for headline inflation of 2.7% against expectations of 2.8% and although core inflation rose to 3.1% from 2.9%, largely due to rising service costs with limited impact from tariffs, the sanguine tone of the report reinforced expectants for a September rate cut.
Later in the week however, the Producer Price Index (PPI) , which measures wholesale prices, accelerated to 3.3% YoY from 2.4% on the headline number and core inflation from 2.6% to 3.7%. The renewed inflation uncertainty saw markets subsequently revise lower probabilities for a September rate cut, from over 90% to 83%, and equities kneejerked lower, dragging crypto along with it.
Despite equities recovering to close the day flat and end the week higher, crypto which had been threatening a decent breakout saw over leveraged positions liquidated and as I write, remains in a consolidative phase, digesting some supply after recent strong gains.
What does this all mean?
The data flow however has done little to change our macro framing of the world. Whilst inflation uncertainty, particularly the impacts of tariffs, will maintain caution at the Fed, the direction of travel remains towards cuts and easier interest rate policy. Indeed, as we wrote last week, we believe the Fed, along with other central banks, have unofficially accepted a higher equilibrium level of inflation. So long as it's not accelerating, the focus currently remains on growth and employment and given high levels of real rates, the Fed’s reaction function is inclined to show more sensitivity to recent signs of labour market deterioration relative to these still high, sticky levels of inflation.
So rate cuts remain on the agenda and we remain of the view, in line with market pricing, that a 25bp cut in September is a lock.
It’s not about the Fed (for once)…
The bigger point, which we’ve also made previously, is that the Fed is not currently the driver of risk. Indeed, we think rate cuts could continuously get pushed out as the US growth remains resilient given that they continue to run war time level fiscal deficits north of 6% 🤯 These deficits are further being funded via the increased issuance of T-bills, maintaining the Yellen style “Treasury QE” drawing idle cash out of the RRP to fund the issuance (more on this below.)
The other drivers remain from the on-going global rate cutting cycle, the ramp in global fiscal plus the ever rising global money supply, all contributing to an explosive rise in global liquidity. Meanwhile the dollar weakness, which remains in a downtrend, continues to ease global financial conditions and given the impact of a weaker dollar typically impacts broader risk with a 3 month lag, then we still have plenty of room to run in this bull market rally across both equities and crypto.
Added to this, there is more risk premium to “leak out” from this market as we climb the tariff wall of worry (China deadline for higher tariffs extended another 90 days this week) alongside the geopolitical fears fading. If Trump can negotiate an end to the Russia/Ukraine war as he’s promising post the Putin meeting, that would be another accelerant for risk for which the Fed pricing has little impact.
All in all, the macro backdrop remains goldilocks and can continue to see this market drive higher.
Fed “Not QE QE” is coming…
One concern however that could cause some temporary volatility relates to the above mentioned “Treasury QE.” With over $1trn in debt issuance to be digested this quarter, Treasury Sec Scott Bessent has followed the Yellen playbook, targeting greater front end issuance which is easier to fund, especially as it draws money out of the Fed’s Reverse Repo Facility (RRP) - Remember, that’s cash parked at the Fed overnight (predominantly by money market funds and banks) and with the increased T-bill issuance, flows into the market to seek higher yields relative to what the Fed pays on the RRP. That has drawn down from over $2trn just over 2 years ago and has been a tidal wave of cash supporting this bull market.
So far in August, it’s drawn down nearly $200bn. However, it now sits at just $33.75bn. Once that reaches zero, this is a big source of funding and liquidity for markets removed. Bank reserves will then be the next required source of funding.
Bank reserves are the funds that commercial banks hold at the Fed plus physical cash held in their vaults, used for inter-bank settlement, regulatory requirements and liquidity provision. Post 2020, there is no minimum amount of reserve that banks are required to hold with the Fed (they wanted to encourage those funds to be leant out to businesses and consumers…moooooar liquidity!) so everything above zero is effectively “excess reserves.”
Yet there are levels of reserves that the Fed considers “ample” below which they potentially start to cause funding issues which could put upward pressure on funding rates, which would be inconsistent with the Fed’s target rate.
Whilst not an exact science, the Fed considers $2.5trn-$3trn as the minimum "comfort zone” below which we could start to see funding stress. Current bank reserve levels are circa $3.3trn so effectively, banks can fund another $800bn before we start to run into funding problems as we saw in September 2019 when repo and bank funding rates spiked sharply higher. When those funding issues occur, the Fed will have no choice but to ultimately provide the market with liquidity in what we term “Not QE QE” - the market will debate whether this is actually QE, but the fact remains that the Fed will ultimately be injecting liquidity and funding the debt issuance.
All roads lead to Bitcoin…
This spiralling deficit and debt will consequently end up on the Fed balance sheet in some form and more “money printer go brrrr” which will continue to debase the currency and drive Bitcoin (as well as equities) to ever more record highs, in dollar terms. There is however a path and as funding stresses start to flare up, can cause a significant negative impact on risk, until the Fed ultimately fulfill their role as liquidity provider of last resort - we are not there yet but we continue to monitor these dynamics and the approach to zero of the RRP starts to bring these issues more sharply into focus.
As we have written previously, the entire, credit based financial system is unsustainable and depends on ever expanding money supply and Fed driven liquidity, with the currency the ultimate escape valve which will keep driving hard assets ever higher.
Fed policy right now will be less concerned with where nominal rates are in terms of supporting the economy and more concerned with the threat of liquidity and funding issues as US debt levels move exponentially higher. Whilst we are concerned that there could be substantial market volatility until the Fed is forced to come in, the Fed have also shown an awareness and willingness, largely as a result of the 2019 repo crisis, to get in front of these issues. Hence we can expect an end to quantitative tightening as a prelude to rising liquidity provision.
TLDR: Whilst people keep trying to call the top for this crypto market, the crazy part hasn’t even begun yet. We are moving closer to the Fed being forced to inject billions of liquidity, accelerating the debasement of the dollar and driving Bitcoin to levels substantially higher from here.
All roads lead to Bitcoin 🚀
Native News
Key news from the crypto native space this week.
In the Ethereum staking space, Lido, whose share of the Ethereum staking market was once so large it raised concerns the protocol was nearing a level considered a dangerous concentration of power, has dropped to a record low. While it's still the dominant force, Lido's market share is now 24.4%, down from its highs in late 2023 when it held 32.3%. That's within striking distance of the 33% level many researchers and Ethereum core developers said would allow a single liquid staking provider to exert disproportionate influence over the blockchain's consensus mechanism. Dune Analytics showed that Figment was the largest gainer of new stakers over the last month.
Coinbase announced that it has completed the acquisition of crypto options trading platform Deribit. This acquisition comes on the heels of a record month of volume and revenue for Deribit – with July ’25 volumes exceeding $185B and roughly $59B of current platform open interest. Deribit recorded over $1 trillion in trading volume last year, and achieved a record-high monthly trading volume of $185 billion in July. This acquisition will enable Coinbase to achieve full coverage across spot, futures, perpetual contracts, and options. Read the full statement from Deribit HERE.
Mesh, the crypto payments infrastructure firm behind PayPal's recent "Pay with Crypto" launch, has raised fresh capital from investors including PayPal Ventures, Coinbase Ventures, Uphold, ByBit, SBI Japan, Overlook Ventures, Kingsway Capital, Moderne Ventures, and CE-Ventures. The latest funding brings its total capital raised to more than $130 million. It comes just five months after Mesh raised $82 million in a Series B round led by Paradigm in March. As with its Series B funding round, much of the new funding round was settled in PayPal USD (PYUSD) stablecoin, utilising Mesh's own technology for instant transfers. Mesh founder Bam Azizi said in a comment "We are set to do for crypto payments what Visa and Mastercard did for card transactions — we're building the first truly global payments network. This is made possible by our SmartFunding technology, which is our primary competitive edge."
Bullish, the cryptocurrency exchange operator that owns CoinDesk, began trading on the New York Stock Exchange under the ticker “BLSH,” on Wednesday. This follows the Bullish IPO, which raised $1.11 billion for the crypto exchange, according to a Reuters report. The exchange sold 30 million shares at an IPO price of $37 per share, giving it a valuation of $5.41 billion. Bullish had first upsized its IPO to between $32 and $33 from between $28 and $31, to raise $990 million. However, the IPO was still 20 times oversubscribed despite this move, which led to an increase in the share price. Bullish is founded by former New York Stock Exchange president Tom Farley and backed by billionaire Peter Thiel and Bullish offers spot trading, futures, and derivatives services.
Institutional Corner
Top stories from the big institutions
Standard Chartered has raised its Ethereum price target to $25,000 by 2028, a major shift from its March forecasts. The bank's Global Head of Digital Assets Research, Geoff Kendrick wrote "We raise our price forecasts, as the backdrop for ETH has improved dramatically in recent months." They now now project ETH price targets of $7,500 by the end of 2025, $12,000 in 2026, $18,000 in 2027, and $25,000 in both 2028 and 2029, up from its earlier $4,000 target for 2025. The reason for the are a heavy demand from institutions and the GENIUS Act legislation. Kendrick noted that institutional buying has occurred at nearly double the pace of Bitcoin accumulation during peak periods. In addition he pointed to treasury companies and Ethereum ETFs purchasing 3.8% of all circulating ETH since June, the US GENIUS Act clearing regulatory pathways for stablecoins, and planned network upgrades as key drivers behind the bullish revision.
The U.S. Securities and Exchange Commission (SEC) has pushed back its decision on Cboe BZX’s proposals for Solana exchange-traded funds from Bitwise and 21Shares this week. The federal agency has used its last full 60-day extension period, setting a final decision date of October 16 for the pending applications. Issued Thursday under delegated authority by the SEC’s Division of Trading and Markets, the orders use identical language for both filings. The orders cite the need for “sufficient time to consider” proposed rule changes that would list Commodity-Based Trust Shares for each fund under BZX Rule 14.11(e)(4). That rule sets eligibility, disclosure, and surveillance requirements for exchange-traded products backed by physical commodities.
The Hong Kong Securities and Futures Commission has set stricter custody expectations for licensed virtual asset trading platforms. It has positioned those requirements as the baseline for a forthcoming licensing regime that would cover standalone virtual asset custodians. Dr. Eric Yip, the commission’s executive director of intermediaries said in a statement on Friday that the move, said to be for the protection of client assets, was done in order for Hong Kong to “foster a competitive, sustainable and trusted digital asset ecosystem.” According to the SFC’s circular, sent to licensed virtual asset trading platforms, reports of “multiple cybersecurity incidents” at overseas centralized platforms have increased significantly over the past year, causing “substantial client losses.”
Charts of the Week
Because charts are just as important as macro.
CME Ethereum futures volume hit a record $118 billion in July. Hat tip The Block for the chart.
TVL on ETH is approaching its highest point since 2021, passing $95b for the first time since January 2022.
Spot Ethereum ETF trading volumes on the rise in recent weeks. Hat tip to The Block for the chart.
Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Senior Product Marketing Manager, Equities at Kraken
Cryptoassets and Payments Supervisor at the FCA
Director, Financial Services at Ripple
Marketing Manager at Wintermute
Senior Policy Advisor - Cryptoassets at the FCA
Head of KYC Operations at Copper
Account Executive New Business at BCB Group
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.
Very interesting insights 🙌