


Welcome to the new subscribers that have joined us over the last week. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: BitGo secures BaFin license, Galaxy Digital lists on the Nasdaq, Anchorage Digital acquires stablecoin issuer Mountain Protocol.
Institutional Corner: UK Government changes for companies offering cryptoasset services, Ukraine finalising legislation to establish a national cryptocurrency reserve, Mastercard partners with Moonpay.
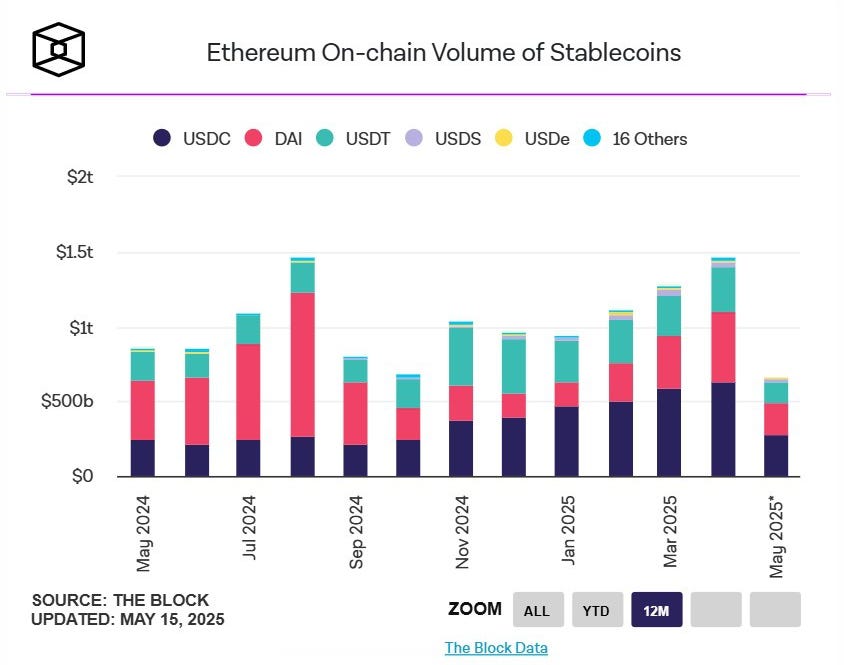
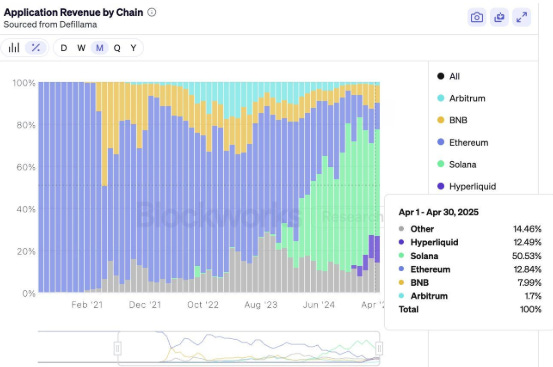
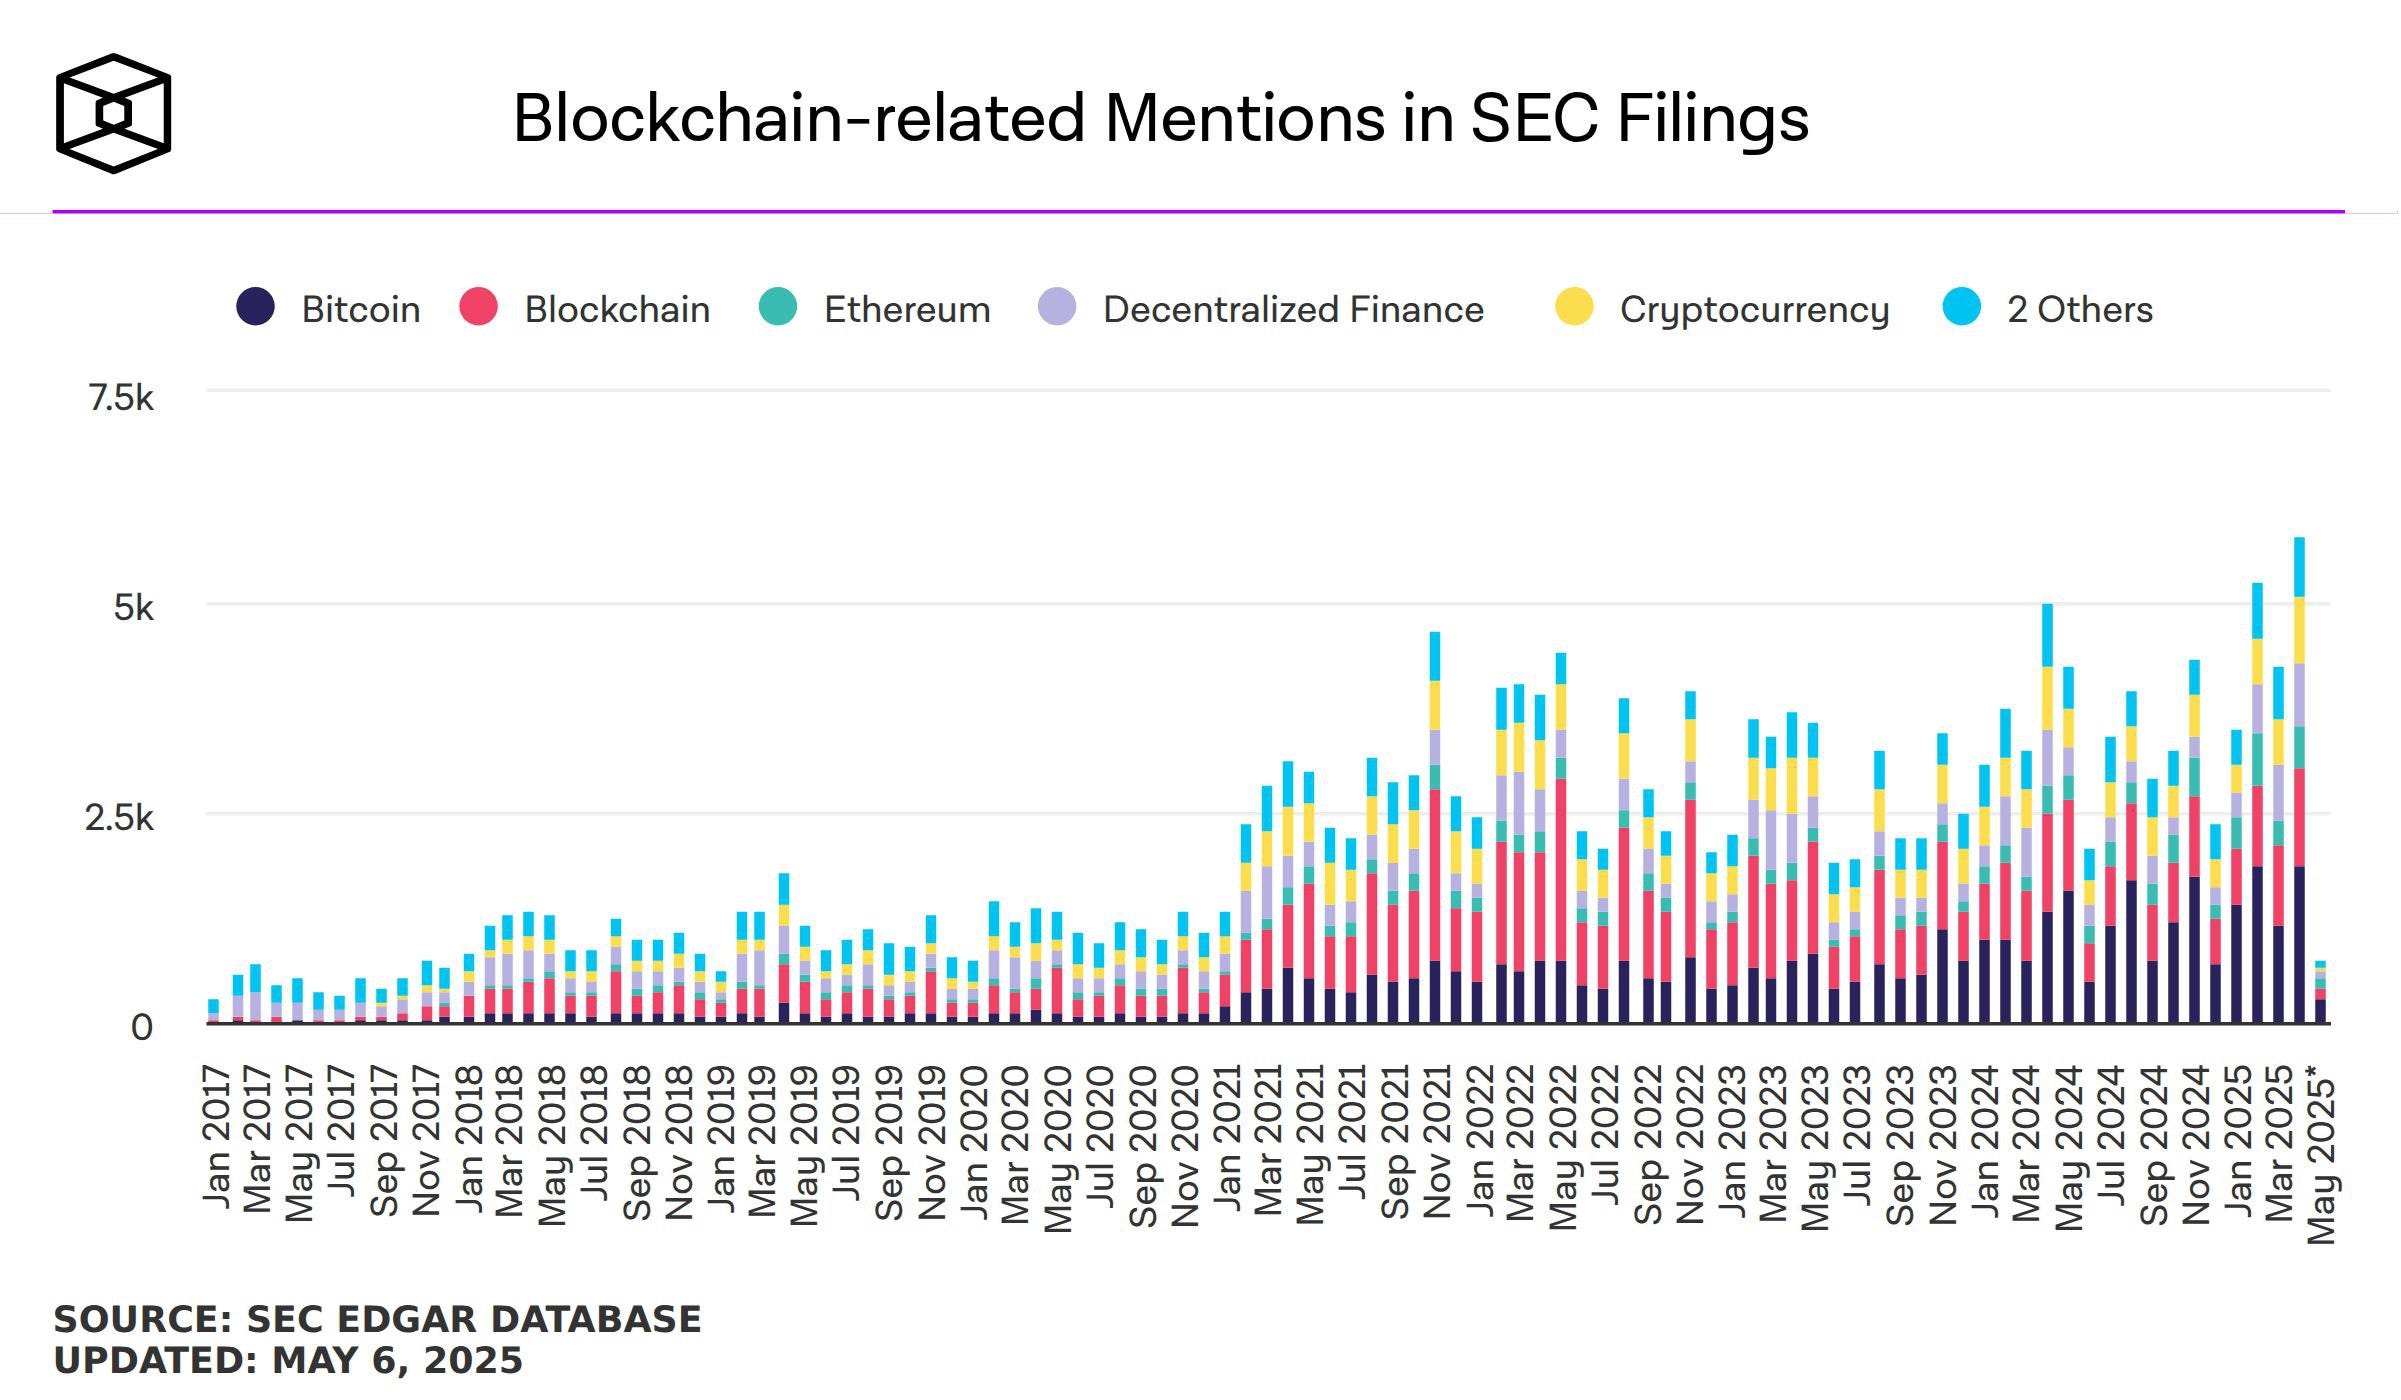
Charts of the Week: Ethereum stablecoin volume reaches a new all-time high, Solana commands just over 50% of total dApp revenue for all of DeFi and mentions of ‘cryptocurrency’ and ‘stablecoins’ in SEC filings hit a record high in April.
Top Jobs in Crypto: Featuring Crypto.com, Chainlink Labs, Revolut, CoinW, Cryptonary and BlackRock.
Macro Update
This is where we connect the dots between macro and crypto.
Pristine Collateral
Markets came flying out of the block this week on the news of a trade deal between China and the US, which Donald Trump hailed as “total reset in relations with China.”
Both sides agreed to drastically reduce tariffs on each other’s goods for an initial 90 day period, with US tariffs on Chinese goods dropping from 145% to 30% whilst China will lower its tariffs on US goods from 125% to 10% as trade negotiations continue.
As we described last week, Trump front loaded the bad news and markets which priced Covid level stress and global disruption, are now having to do a complete 180 and price a more conciliatory Trump, with significantly less global trade disruption and consequently less inflation and less recession risk. In other words, the “left tail risks” are needing to be priced out of the market, which is freeing us up to trade with the MASSIVELY bullish underlying macro dynamic, with the recent dollar weakness facilitating an explosion in global liquidity.
Goldilocks…
Meanwhile, the underlying US economy looks somewhat “goldilocks” with a slowing, not collapsing, disinflationary economy, which has been our base case assumption throughout the year.
To wit, this week's macro data saw inflation come in at a softer 2.3% YoY, its slowest pace since early 2021, while core inflation also came in at a cooler 0.2% on the month, keeping the YoY at a still elevated 2.8%. Goods inflation remains notably soft and headline inflation continues to be held up by shelter which is lagging and trending lower. Wholesale prices echoed the disinflationary tone, with PPI unexpectedly falling 0.5% from March, suggesting firms are absorbing tariff related cost pressures rather than passing them on. YoY, PPI was at 2.4% down from a previous 3.4%. Certainly there are no renewed inflationary flickers to cause the Fed any concern.
On the growth side, retail sales slowed sharply, growing just 0.1% in April, down from 1.7%, with signs that consumers front loaded purchases ahead of expected tariffs. Consumer sentiment also hit its lowest level in five months, with tariff angst weighing heavily on the outlook, which one would expect will start to ease from here. However with jobless claims still showing a resilient labour market, little to justify the macro doomers incessant calls for recession. Indeed, several top tier banks this week, in light of the recent trade negotiations have significantly dropped their recession probabilities.
All in all, a sanguine backdrop to the US economy which will keep the risk premium leaking out of markets and force funds to “gross up” equity exposure and chase performance higher. In the big de-risking episodes, such as what we witnessed in April and August, the de-risking is very “mechanical” in nature and comes in waves of structured selling as the risk model signals, adjusting to the VAR shocks, require broad risk exposures to be reduced (this is what we mean by “grossing down” of risk. Not a rebalancing where total risk exposures remain the same.) We’re now seeing that in reverse with the models dictating that funds “gross-up” risk and so we get waves of mechanical buying that are indifferent to what price is doing on a given day. This will keep equities grinding higher, ceteris paribus.
Of course, all things aren’t equal and perhaps the biggest 2 stories this week have centred once again around US debt sustainability.
Debt sustainability fears…
Despite the talk of this administration looking to reduce fiscal deficits back to 3% (from Biden’s 7%) and get debt under control, details of Trump’s “big, beautiful tax bill” released this week look to be anything but deficit reducing. The proposed spending cuts in the bill of $1.5trn over a decade being dwarfed by the tax cuts which sum to more than $4trn over the same period. Given the softening stance on tariffs which were meant to fill the gap and fund the tax cuts, it increasingly looks under Trump more of the same in terms of running insane levels of deficits.
Perhaps no surprise that 10yr yields jumped briefly back above 4.5% this week. Indeed, as markets adjust to the narrative shift on tariffs, we also need to adjust and reverse the narrative on fiscal deficits and debt reduction, back to the thematic of fiscal dominance, maintaining resilient growth. This will keep pressure on the bond market, yet drive stocks, gold and Bitcoin to ever new record highs. This is the current macro playbook right now.
Whilst the bond market remains a short term risk as yields rise, it will also inevitably lead to financial repression and yield curve control, with a step up in debt buybacks, an SLR exemption to encourage banks to buy treasuries and eventually some form of “not QE QE” from the Fed.
In other words, as the US treasury continues to run unsustainable level deficits, these will have to be monetised in some form leading to ever more liquidity being pumped into markets and an accelerating pace of currency debasement. Bitcoin of course stands to continue to outperform every macro asset in this scenario.
Given this unsustainable debt path, the second big story late Friday was the announcement that Moody’s has downgraded the credit rating of the US to AA1 from its top AAA rating, reflecting concerns about the nation's fiscal stability. Moody’s now joins Fitch and S&P Global in cutting the US credit rating below the triple-A rating.
This could prove problematic for funds that can only allocate to bonds that hold at least one AAA rating from one of the three agencies. No doubt on Monday, the bond vigilantes will be out in force selling US treasuries which will provide a headwind for risk as yields rise.
We think however, after knee-jerk moves, this will likely pass with little broad, lasting impact on risk. Markets will be nervous as when Fitch downgraded the US in August 2023, the S&P 500 fell circa 10% over the following weeks, although that also came coincidentally alongside the liquidity negative event of a rebuilding of the TGA and massive T-bill issuance which was sucking cash out of the market.
However, the US remains the cleanest shirt in the sovereign bond world, with the deepest, most liquid market, so it is unlikely there’s a big rotation out of treasuries as there’s no viable, large enough market for those funds to go. We also believe that a combination of the Fed and Treasury will work to keep Treasury yields in check, which, as per above, leads to an explosion of liquidity. The recent dollar weakness is also likely to continue which is reflexively good for risk and liquidity.
Pristine Collateral…
Bitcoin as the only tradeable risk proxy is under pressure as we write this weekend, anticipating a knee jerk risk sell off on Monday in response to the downgrade. However, we continue to advocate a “buy the dip” response in both equities and crypto as the market still needs to re-weight risk higher in light of the Trump pivot on both tariffs and fiscal.
For Bitcoin, this all continues to feed our bullish long term thesis. US debt is unsustainable, although the US, as a true monetary sovereign will NEVER nominally default. However the default comes via the stealth debasement of the currency. Treasuries remain a relative safe haven in the fiat world, yet Bitcoin is the ultimate, pristine collateral.
Knee jerk risk related sell offs for Bitcoin this week will likely be short lived. As we saw post "liberation day” Bitcoin quickly moved to its “left tail” safe haven hedge against the disruption to a dollar based financial system. When questioning US debt sustainability, gold and Bitcoin are where you want to be.
However, we’ll quickly move back towards the risk-on “right tail” as a treasury market under pressure necessarily requires financial repression and yield curve control, which injects mooar liquidity into the system and debases the currency further.
Expect a volatile start to the week. Yet this is set to catapult Bitcoin to new record highs.
Native News
Key news from the crypto native space this week.
BitGo has secured regulatory approval from Germany's Federal Financial Supervisory Authority, BaFin, enabling the U.S. crypto custody provider to expand its services across the European Union's member countries. This means that BitGo is one of the first American digital asset firms to gain a recognition under the EU's Markets in Crypto-Assets (MiCA) framework. BitGo opened a EU headquarters in Frankfurt in 2023 as part of a broader push to expand across the Eurozone. Since launching its BitGo Europe subsidiary, the firm has secured registrations in countries including Italy, Spain, Poland, and Greece. Its approval from BaFin enables it to operate across all 27 EU member states under a single regulatory framework.
Crypto firm Galaxy Digital listed on the Nasdaq on Friday. The firm has been publicly listed in Canada since 2018. CEO Mike Novogratz said in a statement. “This is more than just a corporate milestone,” CEO Mike Novogratz said in a statement “It’s the fulfillment of a deeply personal bet I made over a decade ago that the financial system was overdue for transformation.” He added “We are moving to the Nasdaq for one simple reason: liquidity, liquidity, liquidity. We’ve loved our time in Canada, but it’s a much smaller capital market.” Read more from Galaxy Digital HERE.
Anchorage Digital said on Monday it has signed a definitive agreement to acquire stablecoin issuer Mountain Protocol as part of its strategy to deepen support for institutional stablecoin use. Anchorage said it plans to fold the Mountain’s technology, team and licensing structure into its own operations, pending closing procedures and regulatory sign-off. Nathan McCauley, co-founder and CEO of Anchorage said "Stablecoins are becoming the backbone of the digital economy. With recent regulatory progress and new institutional use cases, our long-term vision is clear: every business will be a stablecoin business. By acquiring Mountain Protocol, we are taking a significant step forward in supporting institutional stablecoin adoption and advancing a new era of safety, security, and regulatory compliance in the global digital asset ecosystem."
Institutional Corner
Top stories from the big institutions
The UK government announced this week that from 1 January 2026, any companies providing cryptoasset services in the UK will need to start collecting certain user and transaction data. The change stems from the UK’s adoption of the Cryptoasset Reporting Framework — a global standard designed to crack down on tax evasion and bring crypto transparency in line with banking. Platforms will need to identify every user and record their legal details, addresses, and tax identification numbers. They’ll also be required to document every transaction involving UK users or those in other CARF-participating countries, including the value, asset type, quantity, and nature of the transfer. The requirements also extend to foreign firms serving UK clients. Penalties of up to £300 per user will apply for incorrect or incomplete reporting. Read the full announcement from the government HERE.
Ukraine is reportedly finalising legislation to establish a national cryptocurrency reserve. Ukraine already holds Bitcoin worth $4.8 billion primarily from war-effort donations, making it one of the world's largest Bitcoin holders despite not having an official reserve yet. Yaroslav Zhelezniak, the country’s first deputy chairman of its Committee on Finance, Tax and Customs Policy, told local crypto publication Incrypted that he plans to submit a new bill for approval “in the near future,” claiming the bill is in the finalisation stage. The reports come as Ukraine attempts to increasingly formalise its approach to crypto legislation. A 200-page draft bill governing the treatment of digital assets and how citizens should be taxed has been under consideration since late April of this year, though it’s reportedly been temporarily blocked and has not yet been discussed by the country’s parliament.
Mastercard has announced another partnership with a crypto company to provide stablecoin-powered cards, enabling users and businesses to make and receive payments in stablecoins worldwide. Mastercard will work with MoonPay using the infrastructure from Iron, the stablecoin payment provider acquired by MoonPay in March to automatically convert into fiat. In April, the payments giant partnered with crypto exchange OKX and processor Nuvei on a similar project. OKX will launch a new crypto card, while Nuvei, in partnership with stablecoin issuer Circle, will provide merchant infrastructure.
Charts of the Week
Because charts are just as important as macro.
Ethereum stablecoin volume reached a new all-time high in April, hitting $908 billion, as institutions, tech giants, and Trump jump in. Hat tip to The Block for the chart.
Solana commands just over 50% of total dApp revenue for all of DeFi. Ethereum’s fee dominance has fallen to 12.84%.
Mentions of ‘cryptocurrency’ and ‘stablecoins’ in SEC filings hit a record high in April.
Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Institutional Sales Manager UK at Crypto.com
Head of Liquidity at Chainlink Labs
Head of Crypto Entity Gibraltar at Revolut
Crypto Market Researcher at Cryptonary
Director Digital Assets at BlackRock
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.