

Welcome to the new subscribers that have joined us in the last week. The aim of this newsletter is to help you navigate the world of crypto. There’s an incredible amount of information out there so we try to distil it into the things you MUST know each week, covering both macro and crypto.
For snippets and analysis on institutional crypto trading, give our X account a follow HERE.
Onto the newsletter. Here’s what you’re getting this week:
Macro Update: Our latest view on the macro and its impact on crypto markets.
Crypto Native News: Binance Japan and PayPal partner.
Institutional Corner: UK FCA lifts ban on crypto ECN’s, UK government to appoint a digital markets champion, State Street release their 2025 Digital Asset Report, Luxembourg SWF invests 1% of its holdings into Bitcoin.
Charts of the Week: BlackRock ETF tops Deribit for Bitcoin options trading,
Top Jobs in Crypto: Featuring Kraken, Wintermute, Tothemoon, GSR, Keyrock, the FCA, Copper.co and ClearToken.
Macro Update
This is where we connect the dots between macro and crypto.
Surveying the Wreckage
Well that escalated! 😳
Bitcoin made record highs on Monday above $126k as the memetic “Uptober” kicked into gear and broadly across assets the “debasement trade” was gaining momentum with equities and gold continuing to new record highs.
Adding to the “debasement” narrative, the election of fiscal dove Sanae Takaichi who became Japan’s first female PM, saw the Nikkei on Monday rally 4.5% to also clock new record highs. As well as calling for more fiscal spending and tax relief to prop up a fragile economy, Takaichi is also expected to discourage the BoJ from hiking rates.
Consequently, alongside the Nikkei ripping to new highs, the JPY sold off and longer dated Japanese Government bonds (JGB’s) came under pressure. Welcome to the age of fiscal dominance!
Of course, the BoJ has previously stated their willingness to intervene and increase bond purchases if long term yields were to rise sharply. When you have debt/gdp levels over 230% you can’t allow yields to drift too high. This all then leads to continued financial repression, printing money to contain bond yields and the currency becomes the ultimate escape valve.
This process started to escalate this week. Nothing stops this train 🚂
With the US government shutdown on-going, there was little data to provide fresh direction. Fed minutes provided little new, with most participants leaning towards more cuts this year with caution as they look to balance the labour market deterioration against persistent inflation risks. Given recent labour market data, a rate cut for October is nailed on ✅
Elsewhere, data out of Germany showed further signs of weakness as the effects of the front-loading ahead of US tariff’s wore off. A sharp fall in auto production dragging industrial output down, falling in August by 4.3% and reigniting recession fears. Exports also fell 0.5% on the month with declines across all major trading partners.
In France meanwhile, continued political chaos with the French PM, Sebastien Lecornu, resigning just days after forming a new government, citing his inability to build a functional majority in a fragmented National Assembly. Macron subsequently re-appointed him in an attempt to stabilise the situation ahead of a looming budget deadline. This political paralysis comes as France runs a budget deficit in the region of 5-6% with seemingly no ability or willingness to reign in spending. Once more, nothing stops this train!
All change…
As Bitcoin was nicely consolidating after making record highs, we felt smugly confident that the macro thesis was playing out…but then China and Trump spoiled the party!
The actual trouble this time started with China who on Thursday announced new export controls on rare earth elements and related technologies, including restrictions on mining, smelting, recycling, and magnet production, and requiring foreign firms to obtain special approvals if their products contain Chinese-sourced rare earths. This has direct implications for AI and semiconductor firms such as the giant NVIDIA. For context, circa 65% of rare earth metals come from China and an even larger 85-90% of rare earth metals are processed in China.
Given the importance of this threat, Trump consequently warned on Friday that he was “weighing a massive tariff increase on Chinese imports” which sent stocks and crypto sharply lower, but post market close, announced that those tariffs would be 100% on all imports as of 1st Nov.
With crypto the only tradeable market open, we quickly saw a huge sell off, particularly across the alt space which caused a liquidity cascade and the largest liquidation event in crypto history - more than Covid, Luna, and FTX - with estimates in the region of $19bn liquidated in the space of 24 hours 🤯
As we digest these moves and survey the wreckage into what will likely be a volatile few days ahead, we just want to offer our readers a few thoughts and observations here.
Firstly, as we said in April, we look to fade these tariff related headlines which we feel always lack credibility given the scale of global economic interdependence. Trump’s “art of the deal” as he has shown time and time again is to “go big” and focus minds and negotiations.
In particular, in this instance if we compare the situation to April, the threat is more “contained” in the sense that it will not cause markets to price a global recession. Of course however, with the importance of AI and big tech leading stocks to ever new record highs, it has the potential to have a significant short-term impact on risk.
We maintain the view however that with the US and China equally dependent on one another, both playing a strong hand will consequently drive both sides to the negotiating table, despite the early bravado and retaliatory threats. As quickly as the 100% tariff headline hit, we are equally likely to get the headlines of “a great call, maybe the greatest call” and the subsequent compromise and negotiation.
In the meantime, some practical considerations. The VAR shock across assets from Friday’s moves doesn’t look to us so severe to drive a large, prolonged grossing down of risk, but much will depend on how markets open Monday. Still, risk managers will “shoot first and ask questions later.” Given our view that markets remain underpositioned risk, we feel there will be a lot of appetite to buy into these levels however and provide a floor. This is not likely an April redux.
The great thing with crypto is that with autoliquidations and real time settlement, market deleveraging happens quickly (this of course is a blessing and a curse!) - The bandaid has been ripped off and positions adjusted accordingly. We’re actually very impressed with the resilience that majors such as Bitcoin and Ethereum have displayed amidst an historic liquidation event. This is a nod to the “real” buying that has underpinned these, not just leveraged retail degens.
So into this week, one would feel that the knee-jerk across traditional risk markets will be to further gross down risk which could weigh on Bitcoin and broader crypto further.
However, whilst Trump and Xi will no doubt try to compete on the size of their respective…cards they have to play, all of this to us is simply noise to the bigger positive macro dynamic that has underpinned the bull market in both equities and crypto.
Namely, a global rate cutting cycle amidst rising global liquidity, with fiscal deficits ramping. Spikes in volatility will impact “system liquidity” short term which can weigh further on risk, but the underlying dynamic does not reverse and eventually, as situations are becalmed, the liquidity flows in and takes us to ever new highs.
The “debasement trade” that the overpaid suits in Wall Street finally understood last week doesn’t reverse on “tariffs and trade wars.” In fact, it likely accelerates.
So caution into this week as volatility dictates reduced risk taking. Yet the crypto deleveraging has largely completed and for those with a longer term horizon, these are the perfect opportunities and levels to add to your positions.
Indeed, such a flush likely sets us up for the next leg higher and we remain unfazed in our view that this bull run continues into next year’s mid-term elections. Remember, markets are a function of rates and liquidity, everything else is just noise. BTFD 💪
Native News
Key news from the crypto native space this week.
Binance Japan, the local subsidiary of global crypto exchange Binance, has formed a capital and business alliance with Japan’s PayPay Corporation, with PayPay acquiring a 40% equity stake in the local crypto exchange. Binance said the partnership aims to combine PayPay’s 70 million-user payment network with Binance’s blockchain technology to create a connection between digital payments and crypto assets. According to the statement Binance and PayPay plan to co-develop products and services that integrate their technologies, enabling users to experience both fiat and crypto-based transactions more fluidly. Initial initiatives include enabling Binance Japan users to purchase cryptocurrencies using “PayPay Money” directly within the Binance Japan app, and allowing them to select “PayPay Money” as a withdrawal option when selling crypto assets.
Institutional Corner
Top stories from the big institutions
The Financial Conduct Authority’s ban on crypto exchange traded notes, or ETNs, was lifted on Wednesday. They allow investors to gain access to digital currencies via products that are traded on stock exchanges, and track the price of the asset without investors holding it directly. ETNs differ to physical ETFs as they do not have to hold the assets they track. Instead, the provider can aim to match the return of the index however they choose. However, any keen investor looking to get in early will have been disappointed to find that despite the ban lifting, these ETN products are still not available to retail investors. In fact, investors will have to wait until at least 13 October before they are able to but crypto ETNs. The delay comes as a result ETN providers being required to submit their prospectuses for FCA approval before they can offer these products. However, the FCA only began accepting draft prospectuses on 25 September.
Bloomberg reported this week that the UK government plans to appoint a “digital markets champion” to lead efforts to modernise its wholesale financial markets through blockchain technology. Bloomberg reported Wednesday, citing remarks prepared by Economic Secretary to the Treasury Lucy Rigby, that the new role is set to coordinate and lead collaboration between the government and private sector on tokenisation. Alongside the appointment, the government intends to form a new body called the Dematerialisation Market Action Taskforce, which will oversee the UK’s transition away from paper share certificates. Read the full report HERE.
State Street published their 2025 Digital Asset Outlook this week. It revealed “a decisive shift in adoption and strategic commitment among institutional investors toward tokenisation and blockchain-enabled transformation.” The study, based on a global survey of senior executives across asset management and asset ownership, captures sentiment, strategy, and operational readiness across regions and institution sizes. Some of the key takeaways include: Institutional investors are signalling a decisive shift in how they approach digital assets. Nearly 60% plan to increase their allocation in the coming year, and average exposure is expected to double within three years. This momentum reflects growing confidence in digital assets as a long-term investment strategy. Private equity and private fixed income are projected to be the first asset classes to undergo tokenisation. This reflects a strategic focus among institutional investors on unlocking liquidity and efficiency in traditionally illiquid markets. By 2030, a majority expect 10–24% of institutional investments to be executed through tokenised instruments. Read the full release from State Street HERE.
Luxembourg Finance Minister Gilles Roth, revealed the European nation’s Intergenerational Sovereign Wealth Fund (FSIL) has invested 1% of its holdings in Bitcoin. Roth said at the presentation of the 2026 Budget “Recognising the growing maturity of this new asset class, and underlining Luxembourg’s leadership in digital finance, this investment is an application of the FSIL’s new investment policy, which was approved by the Government in July 2025.” Under the revised framework, the FSIL will continue to invest in equity and debt markets, while now also being authorised to allocate up to 15% of its assets to alternative investments. These include private equity and real estate, as well as crypto assets. To avoid operational risks, the exposure to Bitcoin has been taken through a selection of ETFs.
Charts of the Week
Because charts are just as important as macro.
BlackRock’s IBIT has surpassed Deribit as the top Bitcoin options venue, with its open interest standing at nearly $38 billion vs Deribit’s $32 billion.

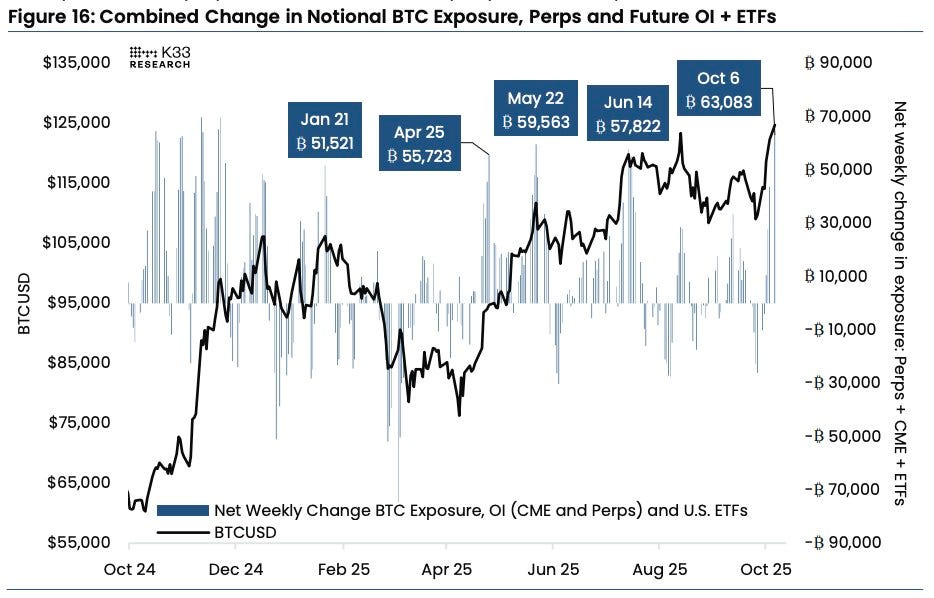
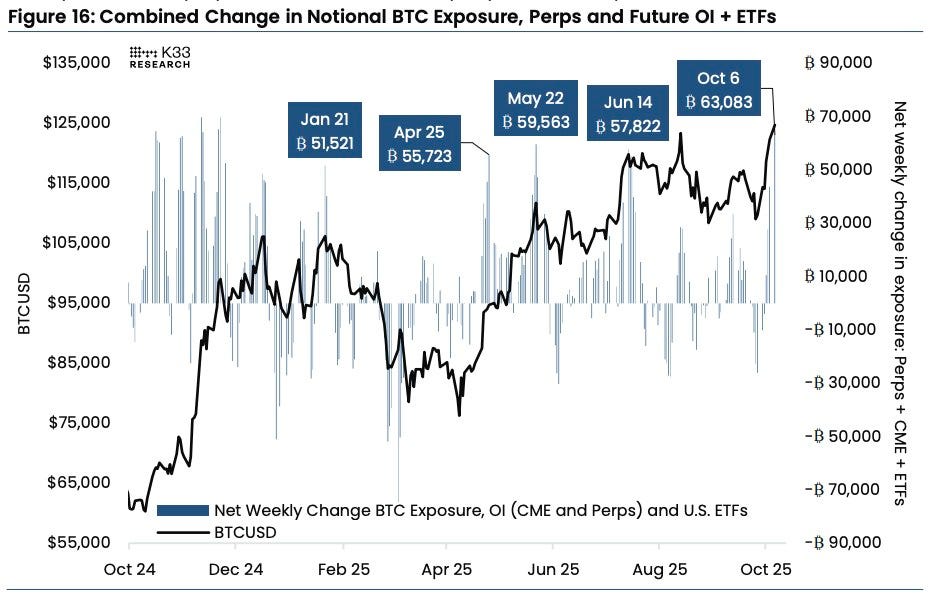
Bitcoin ETF and derivatives exposure surged by over 63,000 BTC ($7.75 billion) in a single week — the strongest accumulation of 2025.
Top Jobs in Crypto
Well, we all want to work in Crypto don’t we. Here’s a bit of help on your job search!
Social Media Manager at Kraken
Crypto Listings Manager at Tothemoon
Trading Operations Analyst at GSR
Product Manager High Frequency Trading at Keyrock
Senior Digital Assets Policy Advisor at the FCA
Head of KYC Operations at Copper.co
Crypto Operations/Client Service Analyst at ClearToken
DISCLAIMER: The content in this newsletter is not financial advice. This newsletter is strictly educational and is not investment advice or a recommendation to buy or sell any assets or to make any financial decisions. Crypto markets are volatile, please be careful and do your own research.
Thanks for the post after the eventful weekend - besides what happened this weekend, I have to say again that I love how you merge crypto native, macro, and institutional topics! Chapeau!